Nutanix CEO: A time of ‘inflection points’
Nov 21, 2022
Show notes
An economic contraction can often correspond to big changes in the technology landscape. Think about the 2008 to 2009 recession, The Great Recession. Amazon’s cloud computing service, AWS, was born the year before the recession, and after the recession, IT became all about cloud computing. Apple introduced the iPhone in 2007, and from 2008 onward, Apple stopped being a computer company and became The iPhone Company.“The 2000 crash, and then the 2008, each of those were, I think, inflection points for tech companies,” says Rajiv Ramaswami, CEO of software maker Nutanix.“I think this is likely to be one of them,” he says of an as-of-yet undeclared economic contraction. The U.S. has seen two quarters in a row this year of declining GDP, year on year, which is one of the criteria for a recession. But the National Bureau of Economic Research, which holds the responsibility in the U.S. of declaring recessions, hasn’t declared one. If and when it does, it may be long after the fact, say, a year from now. Ramaswami was not making an economic prediction. He was taking up my question, What happens to tech if we have a recession?We were talking this past week at Nutanix’s satellite office in New York, in midtown Manhattan, as Ramaswami swung through town on customer visits. The company is headquartered in San Jose in Silicon Valley.“It's great to be out with customers again,” he says. “We’ve been in this environment where we've had remote interactions for a long time, for two years now, and it's time for us to get back out on the road,” he explains. “I don’t think there’s a substitute for that” in virtual meetings. What happens in the inflection point? One thing that happens is a “reckoning,” says Ramaswami, for all the startup companies. “They’re running out of money, and they’re going to have to hunker down, and some of the good ones will raise the cash to see them through and to be still relevant after we come out of this.”I think that’s a conclusion that’s hard to deny. But more broadly, I’m wondering, what happens with the big changes, the thematic shifts that affect whole industries, as with cloud’s rise from 2008 onward?There will be a more “nuanced” approach to cloud computing, Ramaswami tells me. “Historically, people talked about moving [their IT operations] to the cloud as a destination, to go to Azure, AWS, etc,” says Ramaswami. “What they’re really talking about is they like the attributes of what a cloud is, the automation and the services that are available.” NTNX Chart by TradingView This is a bread-and-butter issue for Nutanix, which makes cloud-like software. Nutanix’s programs can “virtualize” a company’s computing and storage and networking so that in the company’s own data center, things run more like cloud computing, meaning, with more efficient use of shared resources, and an ability to work around computer failure.As important, the software can be used as a form of transit, to move a company’s programs, once virtualized, to the public cloud facilities of Microsoft and the rest, and back again. In other words, it’s a kind of shuttle system back and forth, depending on what companies want at any moment in time.His prediction is that as customers try to work more and more in disparate locations, and with a mix of what’s in their data centers and what’s in public cloud facilities, they will use software such as his in order to perform computing in a variety of places, including at a retail store locations or other parts of the “edge,” far away from traditional data centers.“They’ll think about cloud as an operating model, rather than a destination,” he says. “My apps and data are going to be everywhere,” he says of the typical enterprise. “When I say cloud is an operating model, they’d like to operate wherever their stuff sits, apps and data, they want to be able to get that cloud experience.”If there is a recession around the corner, Ramaswami believes the most immediate choice about cloud as an operating model will be how to do it more economically, to save on expenses. Belt-tightening is already happening. Microsoft’s CEO, Satya Nadella, and Google’s CEO, Sundar Pichai, have both told the Street this earnings season that customers are using less of the cloud, as they try to rein in costs. Part of the nuance Ramaswami sees coming down the road is companies pruning what they put in cloud computing environments. “It actually works to our favor,” he says of the comments by Microsoft and Google, “because everybody's looking at costs in a significant way, and especially public cloud costs,” says Ramaswami. “There’s much more of an inclination to be careful about what you put in the cloud, and when you put it there, and what you keep on-prem,” meaning, locally, in the data center. Those choices, increasingly meaningful in a budget-constrained period, will benefit from the Nutanix shuttle system, to pick and choose.“They've got to be much more concerned about making it [applications] portable, so that they can have the freedom of moving back and forth.” “There’s much more of an inclination to be careful about what you put in the cloud, and when you put that there, and what you keep on-prem,” says Ramaswami of budget constraints in the data center. Those choices, increasingly meaningful in recession, are a positive for the software he’s selling, he says. A more profound change, down the road, long after a recession, is that companies are liable to move between different public clouds. They could run an app in Microsoft’s Azure in the morning, and move that same app to Google’s GCP in the evening. That hasn’t happened yet. “Right now, every one of our customers is saying they want to run some stuff on-prem, and then have more than one public cloud provider” as a form of arbitrage, he says. Meaning, an ability to pick, case by case, where they’ll get the best deal. However, “We haven’t seen a lot of movement from one to the other,” he says, meaning, that morning-to-night example of moving an app from Azure to GCP or AWS or another provider. What does it take for that to happen? “They’ll have to start building apps that are portable,” says Ramaswami, referring to his customers. “Historically, people have gone to the cloud because it’s that easy button to push,” he says, the “one-click” experience of Amazon AWS and the others. Just slap down a credit card and get going. That easy button, however, also weds a company to Amazon or Microsoft or Google’s services, he says. The Nutanix software is only part of the puzzle. “The question is what about all the other services that the app needs,” he says, including a database to draw from; a form of data “caching”; a form of search; and a way to pass messages between applications. “The real opportunity is for people to say, I’m going to build with open-source tooling,” he contends. Only open-source code is likely to provide the portability that is needed to free customers. “The good news is, there are a lot of open-source options available” for all those functions. “In fact, ironically, a lot of the public cloud is just proprietary implementations of open-source,” observes Ramaswami. That’s true: Apache Spark, to take just one important example, is a crucial data management program that is broadly available for download, but then Amazon has its own version of Spark.Ramaswami’s goal, over many years, is for Nutanix to sell such open-source tools. “If you look at our own role in that today, one of the things we are doing is to say, We provide a set of tooling on open source databases,” known as “database-as-a-service.” “And we are in the process of making that a common platform that you can use everywhere.” Nutanix, he says, would like to do the same with all the other pieces people need from one cloud to another. “We have the same aspirations to do that with all these other things” such as messaging and search, “a little bit at a time.” The same aspiration, he says, is taking shape at companies that are younger, such as Confluent and privately-held Databricks. They all, like Nutanix, have a vision of things spanning from one cloud to another, without a “lock-in.” It’s what I’ve referred to in past as “trans-cloud,” software that is not beholden to one particular cloud computing service provider. Nutanix, says Ramaswami, is among a cohort of companies with the same vested interest in helping their customers escape the lock-in.“If I’m Confluent, it's in Confluent’s best interest to make that available not just in AWS, but also in Azure, right? And everywhere,” says Ramaswami. The strategy has already been in operation, he notes, at Red Hat, the division of IBM that sells a virtualization tool, called OpenShift. “OpenShift is available across all the clouds, that is their explicit strategy, to create a consistent platform at a level that works across multiple clouds.”The same could be said for Snowflake, the database company that operates in whatever public cloud a customer wants. These things may take years yet, Ramaswami realizes, to coalesce, although sometimes, economic shifts have a way of propelling such change. Could trans- cloud, a more nimble transit between many clouds, be of benefit to Nutanix?“Yes, absolutely,” he says. “We are clearly there at the infrastructure level today,” meaning, the virtualization that shuttles workloads around. “We are trying to go up the stack with database as-a-service,” and to other applications. “Again, the philosophy of making that available everywhere, to make the simplicity, flexibility of choice and portability available across [clouds] — If you're going to continue doing this path” of spanning different clouds, he says, “it's going to help customers, it’s going to help us.”For the moment, in the waning months of 2022, the Street is of course fixated not on sea-change but on what might happen to revenue in a recession. Nutanix is currently in a quiet period, Ramaswami emphasizes, its fiscal first quarter having just ended last month. The earnings report is due out November 30th. Hence, Ramaswami is not making any new financial declarations, he notes, merely reiterating what he has said to the Street on the last conference call.Ramaswami has already told analysts a good chunk of revenue is accounted for in 2023 by software “renewals,” a point he and I talked about last month. As devil’s advocate, I press him on that. Is there a chance renewals could be hampered in a recession scenario, because they could represent too large a line item for some customers?As long as his customers are actually using his software — “and we think most of the customers are,” he says — then, he contends, “they are typically running their enterprise on it, they are running their mission-critical workloads on it, and it's not an optional thing for them.” Not easy to not renew, in other words.What is up for grabs, or up in the air, is new business from prospects. For those companies, there is the vague possibility that belt-tightening, as mentioned above, may bring companies to Nutanix for help. For the moment, he says simply, “It’s new business where there's a lot of uncertainty, and we’ve been prudent enough” in setting a cautious tone with the Street.In the same breath, Ramaswami reminds me that his biggest competitor, VMware, the company that started the virtualization technology phenomenon, is being bought by Broadcom. That will very likely be a source of new customers for Nutanix, he tells me, because in a merger scenario, customers start to worry about what’s happening to their vendor. “It's coming up in every conversation I have had with customers,” he tells me of the merger. “They're all concerned.”It’s not just uncertainty, he says. Broadcom, as an acquisition vehicle under CEO Hock Tan, has developed a certain reputation. “Some of the customers who were customers of CA and Symantec” two large software makers bought by Tan, “have seen what has happened,” he says. “It was not a great experience for them,” he says, without elaborating. The prospect, he says, is the prospect that “they’re [Broadcom] going to try to lock-in” customers to a VMware experience that closes the customers’ options, precisely the opposite of a more flexible, nuanced cloud experience. “I mean, that’s the Broadcom mindset.”It will “take time” for Nutanix to see the benefits of fleeing VMware customers, he says. It takes patience to have conversations and develop relationships. “We say, we’re here to help you,” is the gentle sales pitch. The nice news is that a lot of those prospects “are inbound calls, where we weren’t engaging before” — potentially a whole new customer cohort, in other words. See also:Nutanix CEO: Cloud supply and demand may be the key, Oct. 4th;Nutanix CEO: ‘We are the airbnb of cloud,’ April 27th. From an investor standpoint, Nutanix is having its own inflection point irrespective of the economy. This year just ended was the first year the company achieved positive free cash flow since the company switched to a subscription business model from traditional license sales, roughly four years ago. That is one achievement on a “path,” says Ramaswami, to maintaining “profitable growth,” made somewhat more relevant by economic uncertainty.“It’s very clear investors are rewarding companies that are profitable,” he observes. “We have been on this path for two years, but it so happens that recession is now adding a rationale for why we should be doing this.” “We are committed to going down this path to eventually getting to Rule of 40,” he says, using the Street jargon for when a company has a combination of revenue growth and profit margin that equal 40 when combined.The Street predicts Nutanix this fiscal year increasing sales by just under thirteen percent, for a total of $1.78 billion, and generating an Ebitda margin of about six percent.Another thing, I observe, that happens in a recession, is M&A. Prices of some assets get so low, acquirers get more aggressive. Ramaswami cannot comment on any possible M&A, he says, but offers he is “flattered” by “all the attention we’re getting.” He is referring to a story by The Wall Street Journal’s Dana Cimilluca and Cara Lombardo last month headlined, “Nutanix explores sale after receiving takeover interest.”“The more attention the better, the more people that write about us, the better for us,” he says. That is true, given that for much of the public, Nutanix’s software is somewhat mysterious. As for any deal talk, “It’s not for me to comment on these things,” he says. “It’s for us to focus on building our business, which is what we are doing.”Nutanix shares are down just over ten percent this year, trouncing the Nasdaq Composite Index’s twenty-nine percent decline.
FTX disaster: Guy who liquidated Enron has never seen a mess this bad
Nov 18, 2022
Show notes
An empire run like a teen with secrets to keep: “Mr. Bankman-Fried often communicated by using applications that were set to auto-delete after a short period of time, and encouraged employees to do the same.”
It’s no fun to pile on to Monday-morning quarterbacking disasters, but then every once in a while, a document comes over the transom that is so delicious, it’s hard to resist piling on.
FTX is a crypto-currency exchange that was founded in 2019 by Sam Bankman-Fried and a couple of young friends. It had been, up until a couple weeks ago, perceived as a pillar of the crypto world, if that means anything. It is now in Chapter 11 bankruptcy proceedings, having lost billions in clients’ money.
The vague story leading up to Thursday was that the company had nowhere near the liquid assets people thought it did, and so, no way to safeguard the billions in deposits that FTX’s customers had placed with the company. It appears a hedge fund inside of FTX was secretly taking funds from those depositors and using them to trade — at least, that’s been the surmise of CNBC and other sources to date.
Thursday came the filing in bankruptcy court of a thirty-page document from the person who has taken over FTX to liquidate it, John J. Ray III, who is a career restructuring expert.
Ray presided over the liquidation of the notorious energy failure Enron, among others. Given the amount of malfeasance Ray has seen in his career, it’s quite something to read what he had to say in his dossier.
“Never in my career have I seen such a complete failure of corporate controls and such a complete absence of trustworthy financial information as occurred here,” writes Ray of FTX, after a week going through what little there is of the books.
“From compromised systems integrity and faulty regulatory oversight abroad, to the concentration of control in the hands of a very small group of inexperienced, unsophisticated and potentially compromised individuals, this situation is unprecedented.”
Among the failures Ray describes,
“the absence of an accurate list of bank accounts” — it wasn’t even clear where the company’s cash resided;
Employees bought stuff on the company tab: “In the Bahamas, I understand that corporate funds of the FTX Group were used to purchase homes and other personal items for employees and advisors”;
An audit firm that sounds nuts: “Prager Metis, a firm with which I am not familiar and whose website indicates that they are the ‘first-ever CPA firm to officially open its Metaverse headquarters in the metaverse platform Decentraland’”;
An HR procedure that mixed together employee and contractor records, “with unclear records and lines of responsibility”;
Managing payments worse than a lemonade stand: “employees of the FTX Group submitted payment requests through an on-line ‘chat’ platform where a disparate group of supervisors approved disbursements by responding with personalized emojis”;
“did not keep appropriate books and records, or security controls, with respect to its digital assets” — custodian with no idea of custody;
Managed records like it was Snapchat: “One of the most pervasive failures of the FTX.com business in particular is the absence of lasting records of decision-making. Mr. Bankman-Fried often communicated by using applications that were set to auto-delete after a short period of time, and encouraged employees to do the same.”
There are multiple investigations underway of the whole business, including an SEC investigation and a criminal investigation in the Bahamas, where FTX was domiciled and where Bankman-Fried was apparently residing.
If all this is as bad as it seems, then to my mind, it supports what I wrote over the summer, which is that certain foundational promises of crypto have been broken.
Crypto, it turns out, is not decentralized as its mythology would imply; it’s in the hands of massive exchanges such as FTX and other parties that dominate activity including Binance.
And yet, its centralization has not meant protection for investors, in fact, just the opposite. Crypto is like a throwback to the Great Depression, when there was minimal oversight of banking and depositors were abused on a regular basis without recourse.
Crypto is, in a sense, the worst of both worlds: the manipulation of centralizing forces, but with all the disorganization and lack of security of the Wild West.
Applied Materials rising as quarter turns out much better than feared
Nov 17, 2022
Show notes
Update:
It was a very upbeat conference call this evening between CEO Dickerson, CFO Brice Hill, and analysts.
The outperformance the company displayed in the headline results, relative to its warning in October, was a result of two things. One, the company’s hit from U.S. sanctions against China turned out to be less than expected initially, a decrease of $280 million rather than the $400 million that had been forecast.
Second, said Hill, the company’s “execution in the end of the quarter was almost flawless form a logistics perspective.” Applied, he said, “Got more supply chain parts in at the end of the quarter” that helped boost revenue by a couple hundred million dollars.
Both Dickerson and Hill emphasized that the company has a record amount of backlog, meaning, parts that have been ordered that it hasn’t been able to deliver in a timely manner. While the Street has focused on a slowdown in chips, the story for Applied continues to be supply-chain issues that have held back shipments of equipment.
“We are still supply chain limited across a number of key product lines,” said Dickerson, although, he added, “we expect to continue closing supply gaps over the next few quarters.”
As for that backlog of orders, it was up sixty-two percent, a total of nineteen billion dollars. Nineteen billion dollars is, I would note, equivalent to seventy-three percent of all of last year’s revenue. So, you could think of it as Applied has almost a year’s worth of revenue “in the bag,” so to speak.
Dickerson talked about various markets, and on balance, what he had to say was positive. Yes, there is “weakness in consumer electronics and PCs,” and that will continue to be a weak spot for the chip market into 2023, he said. On the other hand, “automotive, industrial, and power markets remain robust.”
2023 will be a “down year” for equipment sales for the whole industry. And Applied may see its revenue diminished to the tune of two and a half billion dollars, he said, because of the continued sanctions on sales to China.
But, said Dickerson, “we believe that Applied's business will be more resilient, thanks to our large backlog, growing service business, and strong customer demand for our leadership products that enable key technology inflections.”
Moreover, said Dickerson, chip complexity keeps rising on the path to one trillion dollars in chip sales come 2030.
“As technology complexity is increasing, we expect equipment intensity to remain at today's levels or rise further,” he said. “This means wafer fab equipment is likely to grow faster than the overall semiconductor market.”
Previously:
Chip equipment giant Applied Materials this afternoon reported fiscal fourth quarter results and outlook comfortably ahead of consensus, and better than a warning it offered in mid-October.
It was the strongest quarterly showing since August of last year, as the company deals with the global economy hitting demand for chips and thus, chip equipment.
The company’s revenue and profit of $6.75 billion and $2.03 per share was higher than consensus of $6.44 billion and $1.75.
Most interesting, the final revenue number and profit number this afternoon are well above a revised forecast for $6.4 billion, plus or minus 250 million, and $1.54 to $1.78, excluding some costs, that the company had offered in mid-October when it warned that new regulations on sales to China would hamper its results. It would appear things turned out much better than feared.
The revenue beat, and the forecast revenue, are both five percent higher than consensus, the best showing that I can see going back to August of 2021.
Gary Dickerson, Applied’s CEO, said the company is dealing with the global economic and geopolitical situation, and will reduce some of its spending, while nevertheless sounding a chipper tone.
Said Dickerson,
Applied Materials delivered a strong finish to our fiscal year with record performance, and we remain focused on mitigating supply chain constraints and doing everything possible to meet customer demand. Though we are slowing the rate of spending growth in the near term amid geopolitical and macroeconomic challenges, we are making the strategic investments to win the major technology inflections that will enable Applied to outgrow the semiconductor market.
Applied will hold a conference call at 4:30, Eastern, and you can catch the webcast of it on the company’s investor relations Web page.
Applied shares are up two percent in late trading. Shares of fellow chip equipment vendors Lam Research and ASML are also rising.
Applied is a member of the TL20group of stocks to consider. With the small rise after-hours, the shares are up thirteen percent since the inauguration of the TL20.
Nvidia CEO Huang: Cloud expands the company’s reach into enterprises
Nov 17, 2022
Show notes
Huang says selling his company’s full plate of hardware and software, “the stack,” in public cloud facilities such as Microsoft’s Azure, “is just so much more coherent” as a way to sell to enterprises. It’s conceivable the deal also opens up many more prospective customers, thus expanding Nvidia’s total addressable market.
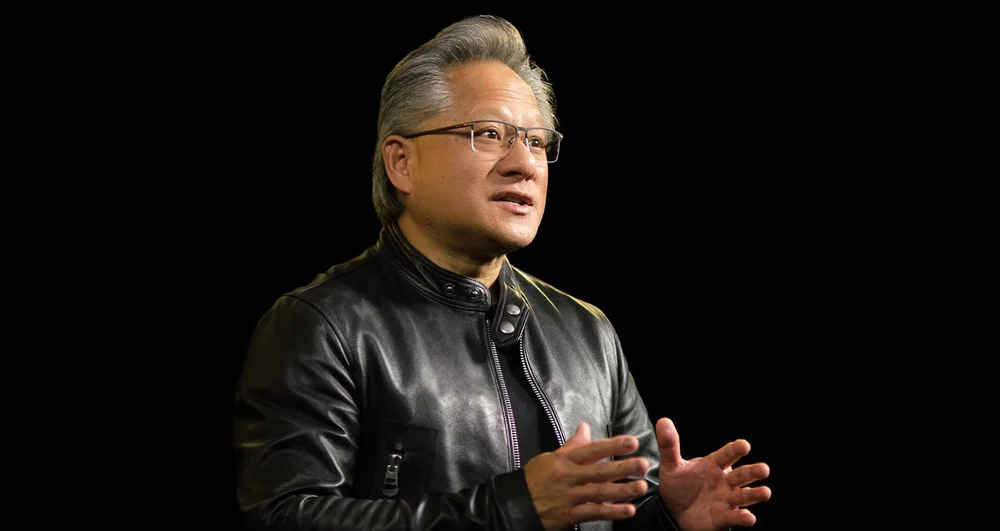
Following a report this evening of better-than-expected quarterly revenue, and an in-line outlook for this quarter, Nvidia’s CEO Jensen Huang was kind enough to take a moment to talk with me by phone. I told him that Nvidia is one of the inaugural picks in the TL20list of great companies to consider owning. “Thank you so much” was Huang’s reply.
Huang can be a person of few words in some interviews. When I asked him what is most important from tonight’s results and outlook, he replied, “We are guiding a better quarter next quarter than this.” What he was referring to was that the company says it is getting its arms around a situation of over-supply of chips for video gaming that caused the company in August to cut its outlook. “We have quickly taken care of our inventory, corrected for our inventory,” he told me.
Huang then recounted the product highlights that he’d also talked up with the Street on tonight’s call:
We have multiple products in the early ramps that are that are home runs. Hopper. Transformer engine. The Ada generation of GPUs — off the charts. Orin has our Drive, our autonomous vehicle platform, to make the auto business into our next multibillion-dollar business. Great stuff going on.
The “Hopper” chip is the latest Nvidia GPU being used for artificial intelligence, which is just coming to market and which racked up impressive test results for AI tasks this month. Huang sees connected vehicles with the Nvidia “Orin” chip as being the next big market for the company after video games and AI.
Huang talked a lot on the call about the cloud service providers, or “CSPs,” including Microsoft. Nvidia had already announced Wednesday morning a deal with Microsoft to offer what Nvidia refers to as its “full stack.” That is jargon for adding to the chips that Microsoft already uses from Nvidia with “tens of thousands” more GPUs, as well as software and chips dedicated to networking together computer systems.
The deal has echoes of the big win that Nvidia had earlier this year with Meta, the owner of Facebook, to buy tons of GPUs for the Research SuperCluster Meta is building for AI. The deal also brings Nvidia’s software to Azure, called “AI Enterprise.” The software acts like a bag of apps for companies, to ease their ability to put together AI into something usable.
I asked Huang what the significance is for his company. Huang can sometimes be frustratingly “on message,” and his response to me was similar to what he said on the call to the analysts.
“We, as you know, always have sold GPUs to CSPs, but CSPs have become two parts,” said Huang. “One is internal, and secondarily, public clouds.” He’s referring to the fact that Microsoft both uses Nvidia chips to develop cloud products and services, and directly rents Nvidia chips to Azure customers who want to use them.
Huang went on to say that Microsoft is going to be “a cheerleader for us” when it comes to pitching the Nvidia chips and software to enterprises, in addition to Microsoft using the chips to run their own AI offerings.
Huang expects that enterprises will increasingly use of AI by renting it from public cloud services. “It’s very clear now that we are at the tipping point of every enterprise company being cloud-first,” as he put it. Basically, that’s because AI programs are so complex, it’s just too expensive and too complicated for most companies to try and do it themselves in their own computer facilities.
That development with cloud is good for Nvidia for two reasons. Deals like the Microsoft deal mean that Nvidia gets a big channel by which to sell its stuff to enterprises. And secondly, reading between the lines, I would deduce that such a deal also means Microsoft may be cooling off on some of its own work on custom chips that they had been pursuing in recent years to try and be self-sufficient. They may be deciding it’s better to just keep buying from Nvidia. If so, it’s a massive win for Nvidia.
What Huang didn’t say, and he also didn’t say when asked the question by CJ Muse of Evercore on the call, is whether selling software will change the financial model of Nvidia’s business, as I had mused in September.
I pointed out to Huang that in the past decade, his company has gone from being what I had considered the scrappy challenger in the data center, trying to unseat Intel, to now being the dominant firm among all chip vendors in the data center, the company in control of the workloads that matter, AI.
How, I asked, does that change in the profile of Nvidia change the kinds of opportunities that Nvidia pursues, or the challenges the company faces?
The question was a philosophical one, but Huang can sometimes be frustratingly evasive when it comes to answering long-winded business questions. In this case, he punted and merely went back to the matter of selling the Nvidia stack in the cloud.
Selling the stack, he said, will make things easier for his customers to use his technology wherever and whenever:
Our ecosystem, the end user, the end markets, the end vertical markets, would be the same. We've always called on, we've always engaged, in part, the end markets. And now we have a coherent, if you will, an organized way of going to the end markets both through cloud and OEMs. And as a result, one architecture and video AI runs on prem as well as in cloud, one full stack. And this way of serving customers is just so much more coherent. And by using the Nvidia stack, they could basically run everywhere. They could run on any OEM server, they can run in any cloud.
What I would take away is that, again, Nvidia expects that Microsoft and the other cloud computing firms, Amazon, Google, Oracle, are going to be a much bigger channel for Nvidia to sell indirectly to enterprises.
Is that a meaningful development for Nvidia? Yes, I think it can be. It can mean that Nvidia, a company that has been selling gear too expensive for many enterprises, now may have a way to price and bundle offerings in the public cloud that will bring its hardware and software within reach of more companies. In other words, it can expand the total addressable market for Nvidia, something all companies love to do.
Nvidia shares are up two percent in late trading. The stock is up almost two percent since I picked it in July for the TL20.
Nvidia’s forecast in-line with Street, says ‘quickly adapting’ to global economic slowdown
Nov 16, 2022
Show notes
Artificial intelligence chip titan Nvidiathis afternoon reported fiscal third quarter revenue that topped analysts’ expectations, but missed on the bottom line, and forecast this quarter’s revenue a tad light of consensus.
The report follows Nvidia having cut its expectations in August because of rising inventory of GPU chips because of slowing video game chip sales as a result of the weakening global economy.
In prepared remarks, co-founder and CEO Jensen Huang told the Street, “We are quickly adapting to the macro environment, correcting inventory levels and paving the way for new products.”
Huang made a number of upbeat remarks about the company’s latest products and markets:
The ramp of our new platforms ― Ada Lovelace RTX graphics, Hopper AI computing, BlueField and Quantum networking, Orin for autonomous vehicles and robotics, and Omniverse ― is off to a great start and forms the foundation of our next phase of growth. NVIDIA’s pioneering work in accelerated computing is more vital than ever. Limited by physics, general purpose computing has slowed to a crawl, just as AI demands more computing. Accelerated computing lets companies achieve orders-of-magnitude increases in productivity while saving money and the environment.
Revenue in the three months ended in October was $5.93 billion, above the company’s own forecast for $5.78 billion to $6.018 billion. Analysts had been modeling $5.78 billion. Profit of 58 cents a share, excluding some costs, was below the average 71-cent estimate.
Sales of chips for the gaming market plunged by fifty-one percent from the prior-year period and by twenty-three percent from the second quarter.
Sales for the data center, including AI, rose by a healthy thirty-one percent, though that was slower than the sixty-one percent in the prior quarter and the eighty-three percent in the quarter before that.
The forecast for this quarter’s revenue is six billion dollars, plus or minus two percents which is just slightly below consensus for $6.074 billion.
Nvidia will hold a conference call with analysts starting at 5 pm, Eastern time. I’ll be interviewing Huang later this evening, so be sure to check back for that.
Nvidia shares rose two percent in late trading to $163.
Also this afternoon, networking giant Cisco Systems beat with its fiscal first-quarter revenue and profit, and raised its outlook for the full year’s revenue and profit above consensus.
Cisco shares jumped five percent in late trading.
Alteryx CFO: In a downturn, customers may need us even more
Nov 16, 2022
Show notes
The modern business of selling software programs is not merely a matter of making a good pitch to prospective buyers. Because the software contracts are renewed every year, or two or three, a vendor must make sure not to lose the customers they’ve already got.
“We really do have a zealot user community,” Kevin Rubin, chief financial officer of software maker Alteryx,says of his customers.
As proof of that, during the company’s annual “analyst day” meeting with the Street in May, he recalls, a panel of Alteryx customers were asked, What would you do if your company chose to move away from Alteryx?”
“The response of one of them,” says Rubin, “was along the lines, ‘You’d have to pry it from my cold, dead hands.’”
Rubin shared that anecdote with me last week over a meeting on Zoom following Alteryx’s third-quarter report November 1st. Maybe you think the hyperbole is overly dramatic for a software tool, but it fairly represents, says Rubin, how Alteryx’s value to customers hasn’t evaporated as the economic uncertainty has arisen.
“I don't want to leave anybody with the impression that we're immune to the macro effects, but I do believe we provide significant value to customers and we'll continue to convey that,” he tells me.
While not immune, perhaps, Alteryx is faring way better this year than a lot of other vendors.
The third quarter was the fourth quarter in a row of revenue upside. And while some firms are trimming their outlook because selling is getting harder, Alteryx raised its forecast for the year for the third time in a row.
At the heart of this delightful streak is the fact that a lot of modern software selling is the phenomenon of renewals, when customers who bought a license to the software years prior have to pay up again to keep using it.
The Street loves renewals because if you can get paid again by the same customer in a periodic fashion, it’s like a guarantee of future revenue, and, sometimes, with little or no incremental cost.
Rubin told the Street on the conference call that renewals of the company’s software were “robust” in the third quarter, without disclosing a quantitative amount. In our exchange, Rubin observes that even in a bad economy, there are things that keep customers coming back. It’s not just that they’re zealots, it’s that the software becomes enmeshed in how companies function.
Alteryx makes data analytics software programs that are meant to “democratize” use of data in an organization. Rather than be stuck with a lame Excel spreadsheet, or, conversely, needing to have a PhD in data science, a person who uses the Alteryx software is supposed to be the everywoman, or man, in an organization, a citizen analyst who can derive meaningful insights with less toil. They can use the programs to get a read on all kinds of trends in how the business is performing.
When customers deploy Alteryx software, Rubin points out, they’re often replacing heavily manual activity like the Excel spreadsheet by “automating that work on a server deep in their IT environments.”
“That becomes incredibly valuable and sticky for those organizations,” he tells me.
Renewals are the latest test of the turnaround engineered by CEO Mark Anderson since he came aboard in October of 2020. Anderson revamped the way the company sells, focusing on the biggest of the world’s companies, and creating a sales culture in which Alteryx reps do a lot more hand-holding and after-sales consulting, to get away from one-shot deals and get larger purchases.
The first test of that approach was whether it would re-accelerate Alteryx’s flagging sales, and it has. Revenue is expected to rise fifty-nine percent this year, to $830 million, after just eight percent growth last year.
The company last quarter had its biggest deal with a new customer in its twenty-five-year history, says Rubin, without disclosing the customer name or the dollar amount.
“The penetration that we currently enjoy in the customers we do have is still incredibly low,” says Rubin, given how many can potentially benefit from the tools. “So, there is a lot of opportunity to continue to grow this business within the existing installed base for many years to come.”
Having reinvigorated the sales effort, the next test is whether those companies would keep renewing even in tough economic times. That’s the test now playing out, and it appears to be going very well.
“Some of the changes that we made were how we support and manage customers, post-deployment, and in particular how we renew customers,” says Rubin. Chief revenue officer Paula Hansen, who came aboard last year, says Rubin, has been instrumental in that effort to stick close to customers, rather than to sell them something and then go on to the next prospect.
“We’ve invested heavily in customer success,” says Rubin. “That organization's sole purpose is to ensure that the most important companies in the world are getting, call it, white glove treatment around what they've purchased, how they're deploying, and then opportunities for future deployments and future ROI with Alteryx.”
The intention of that hand-holding is to make sure that the questions become, says Rubin, “How do I use more of Alteryx and less of other things,” rather than, “How do I reduce my spend on Alteryx?”
In fact, the urgency of using the software should increase, if anything, in a time of stress, says Rubin.
“Organizations know data doesn't get less just because the business environment is less” in a recession, says Rubin. "You know, if you're a company that's going through hardship, you're not asking yourself fewer questions.
“It becomes even more important that organizations have an intense focus on the data around them to make decisions.”
Alteryx’s goal since Anderson shook up the company is to court the Global 2,000 biggest firms, of which Alteryx has about half as customers now. “So there's another half that we believe to be Alteryx customers over time, and then there’s several thousand others that we believe should also be our customers.”
And every one of those new customers and existing customers can be mined to sell even more software by spreading use of the program throughout an organization. “You can’t teach a data scientist how to be an accountant,” observes Rubin, “but you can, through Alteryx, enable an accounting person to operate like a data scientist.”
“You take your unsung heroes within your operational roles and provide them with a toolset that can allow them to operate at a much higher skill level,” is how Rubin puts it. That’s the notion of the democratization of analysis mentioned earlier.
The result is more and more subscriptions can be sold for more and more people in an enterprise to use the programs. Fifteen percent of the workforce inside any enterprise are potential Alteryx’s users, based on estimates the company has compiled with research firm IDC.
“The penetration that we currently enjoy in the customers we do have is still incredibly low,” says Rubin. “So, there is a lot of opportunity to continue to grow this business within the existing installed base for many years to come.”
Of course, revamping a company’s entire way of selling and supporting customers has a cost, and Alteryx’s free cash flow has taken a hit this year, dropping from almost fifty million dollars in positive free cash flow last year to what the Street projects will be negative free cash flow of eighty million this year.
How does the investor base feel about that? I ask.
“In the investor conversations that I've had since we reported, I think there is deep appreciation for the top-line performance of the business,” says Rubin. At the same time, he is aware, “there’s a much greater focus today on profitability and cash flow than six months ago.”
Rubin has emphasized to investors, he says, “our commitment to leverage in our financial model, and driving profitability and cash flow over time.” To that end, the company is slowing hiring now, and is making “significant” real estate changes, basically, reducing its footprint as more people work from home. Those two things, hiring and real estate, are Alteryx’s biggest costs, he notes.
“I think over time you're going to continue to see the business take steps towards the long-term model that we published most recently in May” at the analyst meeting, “and demonstrate to shareholders the growing earnings power of this business.”
That financial model that Rubin put forward in May implies Alteryx will at some point be generating operating profit margin of as much as thirty percent, up from two percent last quarter, and a free cash flow margin that’s positive twenty percent to twenty-five percent — both significant improvements if they come about.
The sharply better results this past year suggest much of the heavy lifting in CEO Anderson’s turnaround push has now been completed. However, “If you ask Mark, he would not suggest at all that we’re done,” Rubin tells me.
“I don't think any of us look at this as if, you know, we're turning a corner per se, and taking a big sigh of relief.
“We have a commitment to delivering a lot of innovation and really scaling this business in a meaningful way,” he adds. "And we're in the early innings of doing that.”
Alteryx’s shares are down twenty percent this year, and basically flat with where the stock was immediately following the earnings report.
The TL podcast for Nov 13th: Picking on Tesla, Upstart baffles, and what happened to FAANG during The Great Recession
Nov 13, 2022
Show notes
Coherent (COHR) and DigitalOcean (DOCN), two TL20 names, both had well-received earnings reports. Upstart Holdings (UPST) had a baffling earnings call. The obsession with Elon Musk is a bit much. And a look back at what happened to the mega-caps of tech during The Great Recession.
TL20: Not dumping Tesla yet
Nov 11, 2022
Show notes
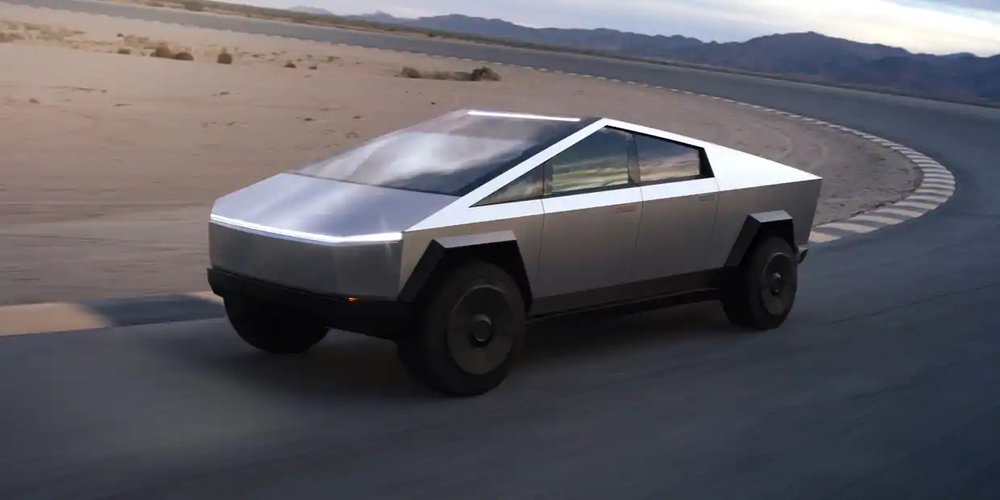
You can say all kinds of things about Tesla, like, for example, the fact that its forthcoming Cybertruck is the ugliest vehicle ever designed. But, like a lot of other assertions, that has little bearing on the shares of Tesla as an investment.
The urge to dump Tesla stock seems to have reached a boil in recent days.
Take analyst Dan Ives of Wedbush Securities. A week ago, Ives defended Tesla when talking to Barron’s Al Root, telling Root that challenges to Tesla were “a near-term storm that will pass.”
Thursday morning, however, in a note to clients, Ives threw in the towel, removing the stock from his “Best Ideas” list. He has, he indicated, finally lost patience with Musk “crushing Tesla stock.”
The issue is Musk’s stock sales in support of his Twitter purchase, which he consummated on October 28th. The sales are not helping Tesla’s stock price at a time when Tesla’s delivery of vehicles is challenged.
Writes Ives,
This is a very nervous few months ahead for Tesla investors as they remain the ones that have been punched again and again by the Musk Twitter antics and the stock now is deep in the investor penalty box until deliveries hit in early January and we get a better sense of the 2023 delivery/production trajectory.
Perhaps waiting till 2023 is good trading advice. I, however, like to look at stocks in terms of fundamental, lasting value.
Tesla stock is in the inaugural batch of TL20stocks to consider, and given the market cap weighting, Tesla is the biggest drag because it is the biggest company. Yet I see no reason to strip it out.
If you were concerned about Musk’s selling of Tesla stock, it’s spilt milk at this point. As mentioned by Bloomberg’sKit Rees and colleagues on Wednesday, Musk has sold thirty-six billion dollars worth of Tesla this year. As Deutsche Bank’s Emmanuel Rosner writes this morning, after taxes, Musk pockets about twenty-five billion dollars, “which just about covers the required capital to complete the deal,” the bulk of the remaining twenty billion being made up by syndicate debt and by investors such as Suadi prince Alwaleed Bin Talal.
More important, I have not seen a fundamental change in Tesla’s profile as a highly successful car maker whose stock was and is reasonably valued.
There are worries about Tesla losing share, especially in China, as Toni Sacconaghi of Bernstein recently emphasized. That’s a valid concern, but competition is never a reason to dump a stock.
The field of young contenders, moreover, is a mess. Rivian Automotive, Lucid Group, and Faraday Future continue to miss expectations as they struggle to get to volume production.
There are practical hurdles to Tesla’s growth that really are meaningful, in particular the need to build out many thousands more charging stations in places all over the world. That’s a serious issue, but so far, it is not a deal-breaker for hundreds of thousands of owners taking delivery of Teslas each quarter.
There are things to quibble with about the product, some large and some small. For example, the forthcoming “Cybertruck,” Tesla’s first pickup, is, in my humble opinion, one of the ugliest vehicles ever conceived. I wouldn’t buy it with your money. But I expect it will find its place in the marketplace, so I have no expectation it will be a drag on sales.
Much more important are a series of investigations into accidents linked to Tesla’s self-driving software, including a Justice Department criminal investigation “over claims that the company's electric vehicles can drive themselves,” according toReuters. It’s early to gauge the potential effects of the investigation, though it is conceivable charges could some day cast a long shadow over Tesla, and that gives one pause.
Beyond the real stuff, many things about Musk as a person get people worked up. He has a big mouth on Twitter, though so do a lot of other people. And to many Twitterati, he is destroying a great service. I for one don’t read Musk’s tweets, and I’ve never loved Twitter; I would just as soon see it disappear. To me, these kinds of things are moot in terms of Tesla stock assessment.
Frustration with Musk is practically an industry, but Tesla has succeeded over many years in spite of his antics. Again and again, promises that Musk made to Tesla shareholders were broken, such as the timing of the introduction of new models. Nevertheless, the company got stronger in the areas that matter most. New products came out, production increased, and Tesla became profitable in the face of enormous skepticism.
At this particular moment in time, Tesla is a powerful company with a leading position in an important industry whose shares have been substantially discounted. That is the core argument for the stock and most of the rest is just noise.
DigitalOcean CEO: It’s hard talking strategy when the Street wants to talk recession
Nov 11, 2022
Show notes
I sat down with Yancey Spruill, chief executive of DigitalOcean, Thursday afternoon, to review what he and CFO Bill Sorensoncommunicated to analysts on Monday.
My main question in these types of interviews, where I have an executive’s full attention for a half an hour, is, Did you communicate what you wanted to communicate?
Yes and no, it turns out. Spruill wants to talk about the company’s ongoing efforts to build a stronger business. It turns out it’s hard talking strategy when everyone wants to talk about recession.
“We made some major strategic actions” last quarter, said Spruill. “The Street is trying to look through that and say, well, absent that, that something’s different in the underlying business.”
To Spruill, the fundamental mission is the same it has been: revenue growth above thirty percent per annum, and a target to get to a free cash flow margin of twenty percent of revenue or better by 2024 from what is mid-teens now.
“Despite war, inflation, currency effects, and weakening economies, we have been able to execute on those objectives, to grow rapidly and to drive free cash flow,” he says.
DigitalOcean, you may recall, is a competitor to Amazon AWS and the other cloud providers. It is focused on being a more economical version of cloud computing. And it is specifically targeting small and medium-sized businesses, who make up the bulk of the company’s seven hundred thousand or so customers.
As I wrote on Monday, Spruill and Sorenson both spent a lot of time reassuring concerned analysts that small and medium-sized businesses are holding up well.
“There’s a lot of skepticism about the durability and resiliency in this type of environment,” Spruill says of the analysts’ attitude. His point is that his customers are no more challenged than, say, Microsoft’s.
“We have looked at historical patterns in other recessions,” Spruill tells me. “What we see is that small and medium businesses perform similar to enterprises.”
As a cohort, he says, they “tend to be like cable and utilities: they tend to be pretty stable; that’s the history of ours.”
If anything, small and medium-sized businesses are ill-understood.
“Most businesses under five hundred employees are not public, they are not well-covered” by the Street, observes Spruill. “I think there is a lack of awareness of how substantial that SMB economy is.” Spruill is fond of pointing out small businesses make up half of the global economy.
His customers, he says, are not going away, but they are grateful that DigitalOcean lets them dial up or dial down their spending every month — known in cloud computing circles as “consumption-based pricing.”
“I talk to as many customers as I can,” he tells me. “They said, ‘Thank you for having this consumption pricing,’ because they are looking at every dollar,” in order to economize.
That’s all well and good, I point out, but isn’t DigitalOcean holding the bag, then, for small businesses? Maybe he never loses a customer to a competitor, but what if his customers cut their spending with his company by ninety percent? That’s not great for DigitalOcean.
Three years ago, DigitalOcean was bleeding cash, observes Spruill, and now is on track to twenty percent free cash flow margin. “To flip like that by four thousand basis points inside of three years is not typical, certainly not in the technology industry and software.”
“You’re right, but we are not levered to a particular country or industry vertical,” says Spruill. The company’s seven-hundred thousand customers are all over the world. “We take our lumps, and we have other customers that are growing.”
By taking one’s lumps, Spruill argues, DigitalOcean is less likely to be surprised down the road. “The thirty-day [payment model], when consumption goes down, you feel it immediately.” That means, he says, “we normalize immediately, whereas, if you have one or three-year contracts” like traditional software vendors, “you get lulled” into a sense of security, and then “it hits you like a wall.”
“I think you’re seeing that in a lot of enterprise contractual subscription businesses,” he says, “that the renewal market is very challenging right now.”
Among the strategic actions his company is taking is M&A. Last quarter, the company bought privately held startup Cloudways. That company is enabling DigitalOcean to add what’s called a “managed service,” which means that it runs cloud computing with much more hand-holding for the customer, more attention.
I asked Spruill how managed services changes the nature of his profit and loss over time. The benefit is both additional revenue but also, perhaps more important, greater free cash flow and greater return on investment.
Cloudways’s gross profit margin, “might be slightly below ours, but not much,” he says. More important, Cloudways is less capital-intensive because unlike DigitalOcean, the company has been reselling other cloud providers’ infrastructure. That’s the opposite of DigitalOcean, which has been investing in property and plant to build its own computing infrastructure.
Now, says Spruill, DigitalOcean can put Cloudways on some of DigitalOcean's own infrastructure, and Cloudways can stop writing checks to providers.
“We can provide the cloud infrastructure instead of a third party, and their costs drop pretty significantly, and their gross margin goes up, becomes closer to ours,” he says. At the same time, the combined entity gets better capital utilization, he says. “We would amortize across the managed service, at a higher price point, and so therefore it’s significantly accretive to free cash flow over time.”
The other strategic move Spruill talked about is selling more data storage along with the cloud computing it sells. Again, to play the devil’s advocate, I asked Spruill whether that means being drawn into a commodity battle with Amazon and Google and Microsoft, companies that can buy storage gear at scale, and that can even afford to lose money on storage if they have to.
“I wouldn’t say anything we do is commodity,” says Spruill. Although DigitalOcean is, on average, half the price for comparable offerings as Amazon AWS, he says, “it’s not really about the price, it’s about adding the functionality that allows them to run whatever type of digital business that needs certain performance characteristics, on our platform.”
Customers, he says, end up using multiple cloud providers, and “typically that is for storage,” he says. “We are talking about closing the gap on those needs” so customers can give more of every dollar to DigitalOcean.
Again, if he can just get the Street not to obsess over recession, Spruill might be able to hammer home to them that strategic things like storage and managed services are a part of an ongoing effort to make DigitalOcean “a free cash flow machine,” as he likes to put it.
“Our view is, any strategic actions you take over the life of the company are additive,” he says. “No one hands you thirty percent [revenue] growth, you have to do it every year.”
Three years ago, DigitalOcean was bleeding cash to the tune of negative twenty-five percent of revenue. Now it’s generating positive free cash flow in the mid-teens. “To flip like that by four thousand basis points inside of three years is not typical, certainly in the technology industry and software.”
“I’m really proud of what we’ve been able to do in terms of getting better asset utilization, and serving customers.”
When will the stock reflect all that? DigitalOcean is one of my inaugural picks for the TL20 list of stocks to consider. The shares are down sixteen percent since that inauguration. And the multiple has been cut by more than half in the past twelve months, to less than five times as a multiple of enterprise value divided by projected next twelve months’ sales.
If the company continues to deliver on the two goals, revenue growth above thirty percent and expanding free cash flow, on the way to revenue of a billion dollars in 2024, “The current stock price is going to be in the rear-view mirror,” says Spruill.
“A lot of the value we’ve been creating here, including substantial free cash flow and huge returns on capital as we scale this, are attractive in good markets and bad,” he says.
“The numbers bear it out, and I’m confident, over time, the market will value that appropriately.”
“We’re rocking and rolling,” adds Spruill. “I have passion about this, these markets can be great; we keep investing and keep the faith.”
Dynatrace CEO: We’re keeping companies away from the cloud precipice
Nov 10, 2022
Show notes
Every software maker is saying this earnings season that it has gotten harder to sell software. Deals are now requiring extra scrutiny, extra signatures, and customers are putting off some purchases for a later date if not canceling them outright.
For many a software maker, that means cutting forecasts and crimping operating expenses. But for most, it is also a chance to reiterate to customers, and the press, why the software is important, perhaps even essential.
Software maker Dynatrace is one of those vendors that has had to trim its outlook. When the company reported third-quarter results last Wednesday, it cut its forecast for its “annualized recurring revenue,” one of those non-GAAP metrics analysts focus on. ARR, as it’s known, is the total value of contracts signed stretching twelve months into the future.
Despite that cut, when I sat down last week on a Zoom call with Rick McConnell, Dynatrace’s CEO, his emphasis was less on what he can’t control — the economy — and more about why, as he sees it, the software he sells is more valuable than ever, even, as he has told me in prior interviews, indispensable.
“The weight and the complexity of data continues to increase because of cloud,” says McConnell. “It’s too much to try and manage using just humans sitting at a dashboard.”
The Dynatrace software, lumped into categories such as “DevSecOps,” and “observabilty,” is a tool IT can use to automate some of the constant surveillance of its applications, looking for problems, looking for things that break, a process that, without some form of automation, is really whack-a-mole, says McConnell.
“Companies are getting hordes of customer calls saying, Oh, my god, your software is down, I can’t make a bank transfer, I can’t buy your product, whatever it might be,” he says, describing what we all have experienced with regularity.
“My hypothesis is that the problem is getting not modestly worse, it’s getting much worse,” McConnell tells me, “because I can’t find the labor, it’s harder to find the problem in the software, I have too much additional software, I have too much infrastructure — it is impossible to manage that in the way they have done in past.”
Companies’ IT departments traditionally try and triage the mess with primitive bespoke tools. Often, they can’t even see what has gone wrong.
“It’s going to get to a precipice where they can’t operate effectively,” and competitors who can operate will pass them by, predicts McConnell, a kind of Darwinian cloud epoch. With labor tight, the talent to keep up with the operations of the cloud is daunting.
“We’re running at full employment,” observes McConnell. “There’s huge wage pressure, it’s hard to recruit people into positions to manage an escalating, —almost exponentially escalating — array of software in a manual way.”
“At some point, that isn’t feasible anymore.”
The idea that companies are in crisis when they use cloud, and heading for potential disaster, and that good software tools become essential, is an intriguing thesis. And yet, it has not spared the stock of Dynatrace nor those of its competitors this year.
Companies are getting hordes of customer calls saying, Oh, my god, your software is down … The problem is getting not modestly worse, it’s getting much worse … It’s going to get to a precipice where they can’t operate effectively.
Dynatrace is down forty-three percent this year, including a six percent drop when it cut its outlook last week. Some are better, some are worse, including Splunk, down thirty-eight percent; Sumo Logic, down fifty-one percent, and Datadog down sixty-two percent, to name just a few obvious contenders. Investors at the moment don’t seem to care how damned important the application.
Even if investors don’t fully grasp it, McConnell is fired up about what his customers say the software has done for them.
McConnell, who was president at Internet bandwidth firm Akamai for over a decade before coming to Dynatrace last year, says he loves to meet with customers. The past few months, Dynatrace held a series of customer events in Vegas, London, São Paulo and Singapore. He met with ten customers a day, over a thousand customers in all. They all have a similar problem of operations being strained.
“I asked the head of a utility company, What do we do for you? He said, You keep the lights on in our country, you let us keep the grid going.” That is a testament to the pervasiveness of software, he says.
“We think of financial companies and services companies as the primary spenders on technology,” observes McConnell, “but these days it’s supermarkets, theater companies, utilities — the world is running on software.
Even in proof of concept bids for business, before a sale, the software has demonstrated its critical utility, McConnell says. A prospective customer, a supermarket chain, was testing the Dynatrace software in real time on live activity at the stores in conjunction with a customer loyalty program.
“It doesn’t sound as critical, but, by God, if I put in my phone number at the register and it doesn’t work, and I don’t get my three dollars and fifty-seven cents, I am frustrated.”
The chain did, in fact, see the system go down, at one point, and “They fixed it as a result of the precision of the answer that we provided as to what the problem was, in fifteen minutes.” The company “immediately” became a customer, he says. “They said, Had we not had Dynatrace in there, that would have taken hours or days.”
If the utility shines through for customers, what is going to keep the investor around in this time of very sour software attitudes? Growth and profitability, presumably, even with last week’s diminished outlook.
“One thing we know is that downward trend cycles recover, and we will see that recovery,” says McConnell of the current economic malaise. Once the recovery comes, “then the question will be, What position are you in to take advantage of it?”
Even with the challenges of the moment, Dynatrace, which is expected to turn in $1.1 billion in revenue this fiscal year ending in March, has been able to keep close to the “Rule of 60,” the Street shorthand for financial profile growth and profit.
Dynatrace had twenty-six percent revenue growth last quarter, and that would have been thirty percent if not for the deleterious effect of the rising U.S. dollar, which depressed reported revenue. The company’s non-GAAP operating profit margin in the quarter was twenty-six percent, which puts the company in a different class from a lot of other software makers that are not even profitable.
Dynatrace doesn’t need to tighten its belt, says McConnell. “We had said a few quarters ago we would accelerate our investments,” he says, meaning, spending. “And we’re largely done with that now.”
“The only thing that it changes is our trajectory of hiring,” he says. “We can just moderate that modestly” because “we believe we have the sales capacity we need at modestly lower sales headcount growth rates to deliver the performance we are expecting in the company.
“A lot of that is due to having been really successful in building out that team over the first half of this year.”
As far as sales growth, McConnell has been adding to the executive team at Dynatrace with seasoned talent he says know how to take the company from a billion dollars annually to several billion. The latest addition is a new CFO, Jim Benson, who also hails from Akamai. He was instrumental along with McConnell in building up Akamai from a billion dollars in annual revenue to over three billion.
“I can’t wait to work with him again,” says McConnell. “He’s our rockstar, just delighted to have him at Dynatrace.”
What no one can control is what valuations the Street will currently assign, which are way lower across the board for all software stocks. As a multiple of enterprise value divided by the next twelve months’ projected sales, Dynatrace trades for just under eight times where a year ago it was fetching twenty-one.
“Is that the right valuation for a promising young tech company that’s growing fast and is already profitable?” I ask McConnell.
“I can’t give predictions on multiples, but I can say that I really believe — firmly — in the long-term optimism and capabilities of our business; that’s why I’m delighted with our ongoing execution even amidst economic uncertainty.”
The investor feedback he hears these days is, “Where is the bottom of the market, where we can see a re-acceleration in overall multiples and stock prices?”
Maybe that takes a couple more or a few more quarters, he says, but, “One thing we know is that downward trend cycles recover, and we will see that recovery,” says McConnell. “It may take one or two more interest rate changes, but downward trend cycles always recover.”
Once the recovery comes, says McConnell, “then the question will be what position are you in to take advantage of it?” He intends for Dynatrace to be well-prepared.

 Our TOPPODCAST Picks
 Stay Connected