TopPodcast.com
Menu
  • Home
  • Top Charts
  • Top Networks
  • Top Apps
  • Top Independents
  • Top Podfluencers
  • Top Picks
    • Top Business Podcasts
    • Top True Crime Podcasts
    • Top Finance Podcasts
    • Top Comedy Podcasts
    • Top Music Podcasts
    • Top Womens Podcasts
    • Top Kids Podcasts
    • Top Sports Podcasts
    • Top News Podcasts
    • Top Tech Podcasts
    • Top Crypto Podcasts
    • Top Entrepreneurial Podcasts
    • Top Fantasy Sports Podcasts
    • Top Political Podcasts
    • Top Science Podcasts
    • Top Self Help Podcasts
    • Top Sports Betting Podcasts
    • Top Stocks Podcasts
  • Podcast News
  • About Us
  • Podcast Advertising
  • Contact
Not in our directory?
Add Show Here
Podcast Equipment
Center

toppodcastlogoOur TOPPODCAST Picks

  • Comedy
  • Crypto
  • Sports
  • News
  • Politics
  • True Crime
  • Business
  • Finance

Follow Us

toppodcastlogoStay Connected

    View Top 200 Chart
    Back to Rankings Page
    Business

    Insureblocks

    blockchain & smart contracts in industries across the world

    Advertise
    • Apple Podcasts
    • Google Play
    • Spotify

    Latest Episodes:
    Ep. 178 – SDX – SIX’s regulated digital asset exchange platform Apr 25, 2022
    Show notes

    Michele Curtoni heads the strategy and new business development at SDX, SIX’s regulated digital asset exchange platform, which is part of the SIX Financial Group, the financial market infrastructure of Switzerland. In this podcast we discuss a wide range of topics from wholesale CBDC projects, cryptocurrencies and a lot more from the optic of a regulated digital asset platform.

    What is blockchain?

    The first time Michele was explained what is blockchain was in 2014/15. At that time it was described to him as an append only data structure. It’s an Excel where you never can delete a row, you can only add them, but you can look up whatever you wrote before and what other people wrote before it. It has a chatter effect where you have to validate what is heard by the participants in a “room”.

    In terms of how it applies to the financial industries, it comes down to the ledger, the compression of the ledger, intermediaries and malicious actors onto a network and how the validation of the blocks would work.

    SIX and SDX

    SIX is the financial market infrastructure of Switzerland. SIX operates the infrastructure for the Swiss and Spanish financial centres. The BME (Bolsa de Madrid), the stock exchange of Spain, was acquired by SIX in 2020. SIX runs the CSD, central securities depository, in Spain, the clearing house called X-Clear and the listed exchange.

    Michele describes, SDX as a bet that SIX took a few years ago to start capitalising on the blockchain revolution. There was a recognition that SIX needed to prepare itself for this digital revolution of digital assets and crypto currencies hitting the traditional FMI space. SDX was built to cater for this new business, of both crypto and digital securities by creating a kind of CSD on blockchain to tokenise those digital regulated securities.

    In September 2021, FINMA, the Swiss Financial Market Supervisory Authority issued two approvals to operate financial market infrastructures based on blockchain. Specifically, FINMA has authorized SIX Digital Exchange AG to act as a central securities depository and the associated company SDX Trading AG to act as a stock exchange. This was the first time that a licence has been issued in the Swiss financial centre for infrastructures that facilitate the trading of digital securities in the form of tokens and their integrated settlement. This proved that you can build a CSD under a specific regulatory regime, using a private DLT

    This allows for atomic settlements, trading and settling at the same time, and for smart contract enablement.

    In November 2021, SIX issued its own dual tranche bond to fund the M&A transaction to acquire BME. The CHF 150m ($162m) bond was composed of a CHF 100m digital bond listed on SDX and CHF 50 million conventional bond listed on the SIX Swiss Exchange. The splitting of that bond in this manner was voted by the participants. The bond was oversubscribed and the rating was equal across the two channels.

    Wholesale CBDC projects

    SDX participated in two wholesale CBDC projects. Project Helvetia, was conducted by SND, the Swiss National Bank, the Bank for International Settlements (BIS), SIX/SDX and 5 commercial banks. The project looked at introducing a Digital Swiss Franc as a CBDC in Switzerland.

    Project Jura, the second wholesale CBDC project involved Banque de France, BIS, SDX and the Swiss National Bank. The project aimed to enable instant settlement of foreign currency transactions as payment versus payment (PvP) and the use of wholesale CBDC to pay for tokenized commercial paper transactions as delivery versus payment (DvP) with immediate settlement. The project also aimed to explore how cross border central bank movements of assets and money would work.

    It looked at the concept of DvP, of commercial paper, in this case issued under French law against a Euro CBDC and then a PvP of that Euro CBDC versus the Swiss Franc CBDC. So, a transfer of assets versus cash and then cash versus cash.

    The project proved that such kind of transactions were possible but achieving scale is a whole other question.

    For example, if assets and cash aren’t on a similar ledger you have the question of interoperability that needs to be addressed. When they are on the same ledger you enter into the topic of whether or not these assets have to be digitised? Cash is easy to digitise but for securities that’s a different question. For example, for a security where does the security sit on the CSD? Is the CSD allowing for tokens? With SDX yes, but with others, no. Thus, you need to be building more digital securities platforms than SDX. So, the benefits on cash do not really help the financial system unless you have digital securities and vice versa.

    SDX and crypto currencies?

    In December 2021, SDX announced a joint venture with SBI Digital Assets, a fully owned subsidiary of Japanese banking giant SBI Holdings.

    The joint venture, Asia Digital Exchange (ADX), would be set up in Singapore through a crypto issuance company and aims to launch an institutional spot crypto exchange.

    The new undertaking will offer a range of digital asset products and services in the form of tokenized securities such as digital bonds, digital equities and digital securitized loans.

    SDX sees ADX as a potential partner in the future as a consumer or as a servicer of the SDX business.

    SIX already has more than 60 ETPs, exchange traded products, based on cryptocurrencies. SDX, being a natively digital company as big crypto plans of its own.

    SDX plans for the next 12 months?

    SDX frames itself in three big pillars:

    • Digital securities: growing the FMI business
    • Crypto
    • Exploratory business for new business models enabled by blockchain such as a carbon registry, tokenisation of art, NFTS for institutional investors, DeFi and real estate

    Ep. 177 – Why decentralised finance matters and the policy implications? – OECD Report Mar 27, 2022
    Show notes

    Iota Nassr is a policy analyst at the OECD within the financial markets division. She currently manages the FinTech experts group of the OECD Committee on Financial Markets, leading the analysis around anything that has to do with digitalization of finance. The OECD Report “Why decentralised finance matters and the policy implications” is product of the committee’s expert group composed of representatives of the 38 OECD members coming from Central Banks, Ministry of Finance and other financial authorities.

    What is blockchain?

    Iota’s definition of blockchain hasn’t changed much since her previous podcast on Insureblocks on “Tokenisation of Assets and Potential Implications for Financial Markets – OECD Report” on the 13th of June 2021. She still sees blockchain and DLT, more broadly, as a way to record, share information and to exchange value in a decentralised manner without the need for trusted central authorities or intermediaries.

    However now she believes the emphasis is now more on the programmable nature of decentralised distributed ledger technologies and the level of disintermediation involved in the different networks and structures that we observe in the market.

    Why this report?

    The Summer of 2020, also known as the DeFi summer caught the attention of the OECD. This was due to the exponential growth they were observing and the level of participation of retail investors in what is a very highly volatile market that is devoid of the traditional safeguards that are in place for investors and consumers in traditional financial markets.

    The feedback loops they have observed between DeFi and mainstream crypto such as Bitcoin, Ether ,the main stable coins along with the recycling of profits between the two kinds of environments, made it increasingly critical for the OECD to have a look at this space.

    The final reason for analysing this market was the growing institutionalisation of crypto assets, which may be increasing risks of interconnectedness between decentralised and traditional finance. This report’s objectives is to like into DeFi models to understand the risks, opportunities and implications for traditional finance.

    What is Defi?

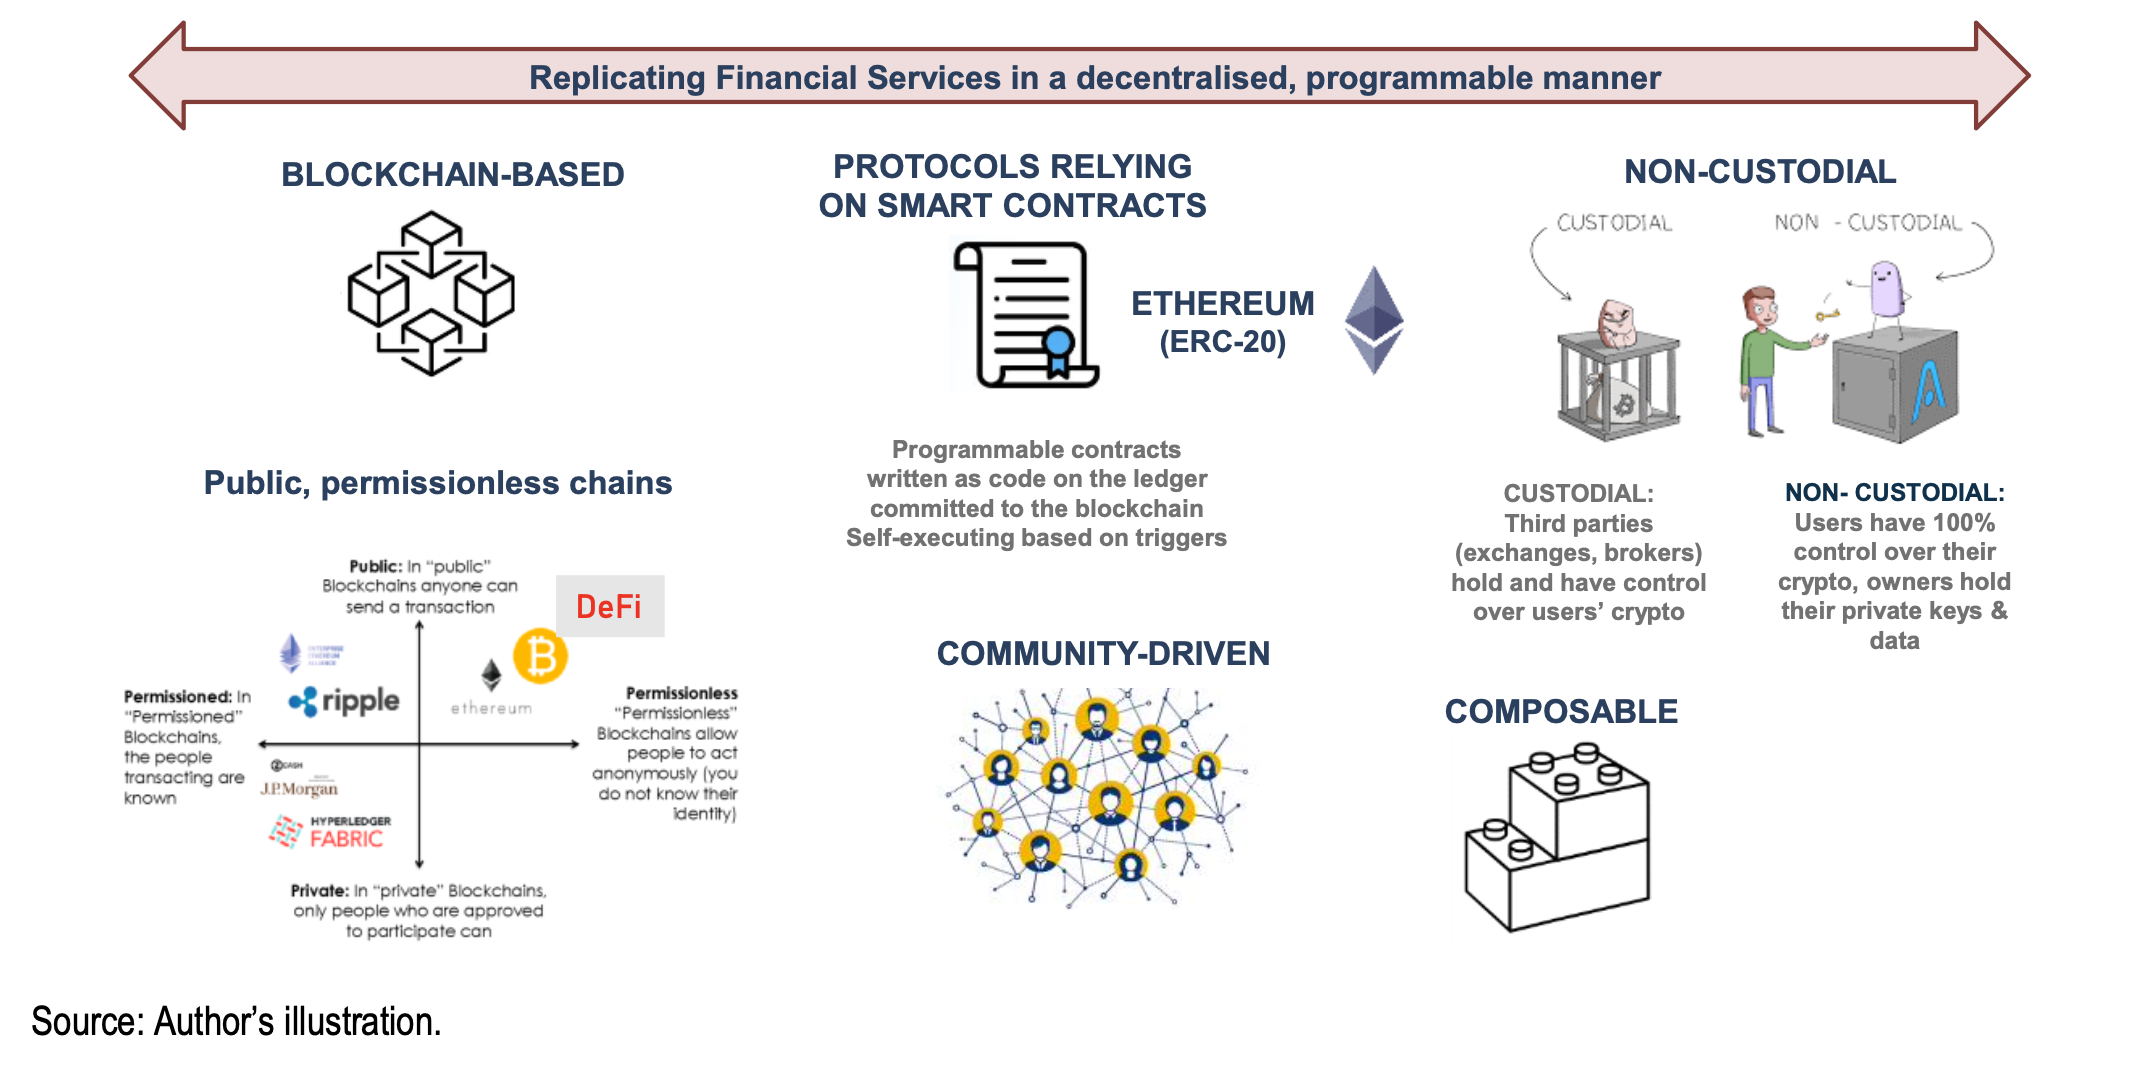
    DeFi, decentralised finance, claims to replicate what is known as traditional finance in a decentralised way in an open way through applications built on Ethereum and increasingly on other blockchains.

    There are two possible misconceptions around DeFi. The first is that not all DLT based financial applications are DeFi. So the fact that a financial application is built on the blockchain does not make it by default part of DeFi. The second misconception has to do with self proclaimed DeFi applications that may not be truly decentralised. The degree of decentralisation varies from one project to another.

    The report defines three key defining features:

    • Non-custodial: The protocols and the applications have a non-custodial nature. There is no central authority or other intermediary gains access to or control over participants’ digital assets; instead, participants manage their private keys, and therefore their digital assets, directly.
    • Self-governed and community-driven: Most DeFi protocols are open-source and allow the community to review and further develop the code underlying the protocols. This happens through the use of governance tokens.
    • Composable: Existing components of DeFi networks (i.e. digital assets, smart contracts, protocols and applications built on top of the protocol layer) can be combined to create new applications. The open source nature of DeFi applications is a critical enabler of this attribute, as it allows everyone to look at the code and use it to create new applications.

    Source: OECD Report Author

    Most popular DeFi products

    The concept of liquidity mining and of collateralized lending on the DeFi lending protocols was one of the most obvious ways for investors to earn yield on the back of mainstream crypto that they already held. Because of that collateralised lending rapidly became the fastest growing DeFi product followed by decentralised exchanges (DEX) while other applications such as derivates and synthetics also grew in popularity.

    Institutional investors alongside decentralised exchanges are also participating in collateralized lending.

    Growing interconnectedness between crypto and traditional markets

    The OECD Committee on Financial Markets has noticed a shift in traditional financial institutions from the education phase of what is Bitcoin and what is blockchain to the investment phase where they are allocating parts of their portfolio in such assets. The Committee is looking at the potential risk of growing interconnectedness between decentralised and traditional finance which could lead to the potential spill over to the traditional financial system and the real economy.

    Iota gives an example that if there was a generalised distress in the crypto market, an investor who is exposed to losses on his crypto related investments may have to close his positions on other parts of his portfolio therefore propagating this kind of shock.

    KYC & AML

    this is a bit of a paradox because we know that the blockchain allows for complete transparency. And all transactions are traceable and verifiable on the chain. But they are verifiable and traceable in pseudonymous way, we don’t have recourse to the identity of the participating node. And this is what makes it complicated.

    Unlimited leveraged trading of crypto-assets

    The possibility to engage in almost unlimited leveraged trading of crypto-assets is one of the main risks involved in DeFi. Whilst current DeFi applications benefit from high levels of over-collateralisation, it could be expected that further growth of the Defi market would bring it that level down to allow for better capital efficiency, as competition would put pressure on tokenomics involved in DeFi protocols. The volatility of crypto-asset prices intensifies the fragility of the DeFi market, and volatility spikes in the price of main crypto-assets pledged as collateral for borrowing and leverage or provided as liquidity for yield farming can induce massive automatic liquidations in DeFi protocols. Such liquidations can have a domino effect on investor holdings across the board, and may even have spill over effects in traditional financial markets.

    Positives that DeFi applications can provide to financial markets

    DeFi applications have the potential to provide benefits to financial market participants in terms of speed of execution and transaction costs, driven by the efficiencies produced by DLT-technological innovation and disintermediation of third parties replaced by software code of smart contracts.

    The governance arrangements along with the open source nature of DeFi allow for possibly more equitable participation of users and the promotion of innovation in financial services.

    Drivers of institutional investors in digital assets

    The OECD has identified three forces that underline and contribute to this increased institutional investor interest in digital assets of which the majority is in Bitcoin, followed by Ether.

    The first force has to do with this search for yield in what was until recently a prolonged low interest rate environment. The same kind of speculative forces, the same kind of fear of missing out that led retail investors has been driving also institutions.

    The second reason is the potential of crypto assets for diversification and portfolio optimization. Investors perceive as uncorrelated nature of returns, they wish to diversify their portfolio by adding this kind of non-correlated assets such as crypto. However, the OECD’s report dismisses this hypothesis as they have been seeing a growing correlation between mainstream crypto assets and the large traditional asset class.

    The third reason is the perceived benefit of crypto for institutional investors as an inflation hedge. However, the OECD’s analysis finds that the main crypto assets have not really performed as effective inflation hedge, but that does not prevent investors from perceiving it as a good inflation hedge which drives them demand for Bitcoin in particular

    How can existing regulatory frameworks work with decentralised structures?

    Some of the tools that are being used in centralised settings may need to be redesigned in order to be interoperable and compatible with decentralised structures.

    One other approach is to re-centralise DeFi in order to get some kind of comfort from a supervisory and regulatory standpoint without necessarily completely undermining decentralisation. Some forms of centralization already exists in such networks and could be considered as this single regulatory access point. For example DAOs could play this role or majority governance token holders.

    Other tools could be around regulatory compliance embedded in code, allowing and or demanding the audit of smart contracts, having mandatory reporting in an automated fashion through machine readable formats.

    Roles policy makers can have in DeFi

    The report lists a number of roles policy makers can provide:

    • Financial education
    • Improved disclosures in DeFi applications can be seen as a first easy step towards greater protection of participants. For example disclosures on whether or not someone holds an admin key and what kind of rights it gives its holder.
    • Increased regulatory clarity
    • Identify new rules if policy gaps are found and identified.

    Ep. 176 – Etherisc’s flight delay blockchain insurance in production Feb 06, 2022
    Show notes

    In 2016, Etherisc was one of the first companies to launch a real world use case for a flight delay insurance policy on a public blockchain. Regulatory and lack of stable coin hindered that early solution. In 2017, they relaunched along with an insurance partner but still had challenges. In today’s podcast, Christoph Mussenbrock – CEO & Founder of Etherisc shares with us what they have learned since 2016 and why their 2022 launch is going to win.

    What is blockchain?

    Blockchain is a technology which allows you to keep a distributer ledger of transactions. It comes in two flavour as either a public or private blockchain. In a public blockchain, all participants can validate transactions independently thus creating a new level of trust. Some of these public blockchain such as Ethereum offer programmable computing, which enables the running of programs such as smart contracts. Smart contracts can be used to programme a complete insurance business process on top of blockchain which is what Etherisc is doing.

    About Etherisc

    Over the years, Insureblocks has featured a number of Etherisc’s spokesperson such as Stephan Karpischek, Renat Khasanshyn and Michiel Berende.

    Etherisc was started in 2016 by Chistoph and Stephan when they develop a small prototype for flight delay insurance that they presented at DEFCON2, an Ethereum Developer conference in Shanghai. At that time it was one of the first insurance real world applications. Soon after developing this prototype the Etherisc team started encountering legal and regulatory issues. Whilst tackling those issues they decided to build a whole platform where anybody could build products on top of it, something akin to an operating system for insurance products.

    This platform is an open-source common infrastructure, the Generic Insurance Framework (GIF), which includes shared smart contracts, product templates, microservices and the native cryptographic token (DIP) to enable the seamless and efficient creation of decentralized insurance products, with increased transparency and fairness for all parties.

    Over the last few years they have developed a new legal model which for the German market and most other European countries which enables them to run insurance products without needing an insurance license which can be quite expensive with a large number of regulatory compliance issues.

    This new legal model enables Etherisc to design insurance products without the need of a formal insurance license with the approval of the German financial regulator.

    Projects currently hosted on Etherisc’s open-source Generic Insurance Framework include FlightDelay Insurance, Crop Insurance, and Hurricane Protection.

    Flight delay insurance, relaunch?

    When Etherisc’s flight delay insurance launched as a prototype in 2016 it had no legal framework and no stable coin to leverage for it to have a compelling proposition. The lack of a stable coin meant a highly volatile risk with the use of Ethereum coin leading to insurance payout of either nothing or very large sums of money.

    In 2017, Etherisc partnered with Atlas Insurance PCC to address the lack of an insurance license. Etherisc could effectively rent the Atlas Insurance license. However, a Stamp Tax of $15 for each policy meant launching the flight delay proposition was not feasible as the average premium was around $15.

    It was only in 2022 that Etherisc could successfully launch their Flight Delay product with a solid legal framework and a stable coin like DAI with which it could run its transactions on.

    Thoughts on Fizzy from AXA

    In August 2018, Insureblocks featured Fizzy, AXA’s flight delay insurance policy, which subsequently closed in 2020. You can listen to their learnings of that experience on an Insureblocks podcast.

    Christoph view on that is that AXA like other traditional financial companies, typically have very complex internal IT systems which are heavily regulated.

    Their IT managers and security managers, who are responsible to keep the systems running, are not comfortable with blockchains, and even less with public blockchains. Christoph states that it is completely against their thinking to have an open, anonymous platform that they can’t control and where they don’t run the nodes. Thus, it’s very complicated for a traditional financial institution to integrate with a public blockchain.

    User experience

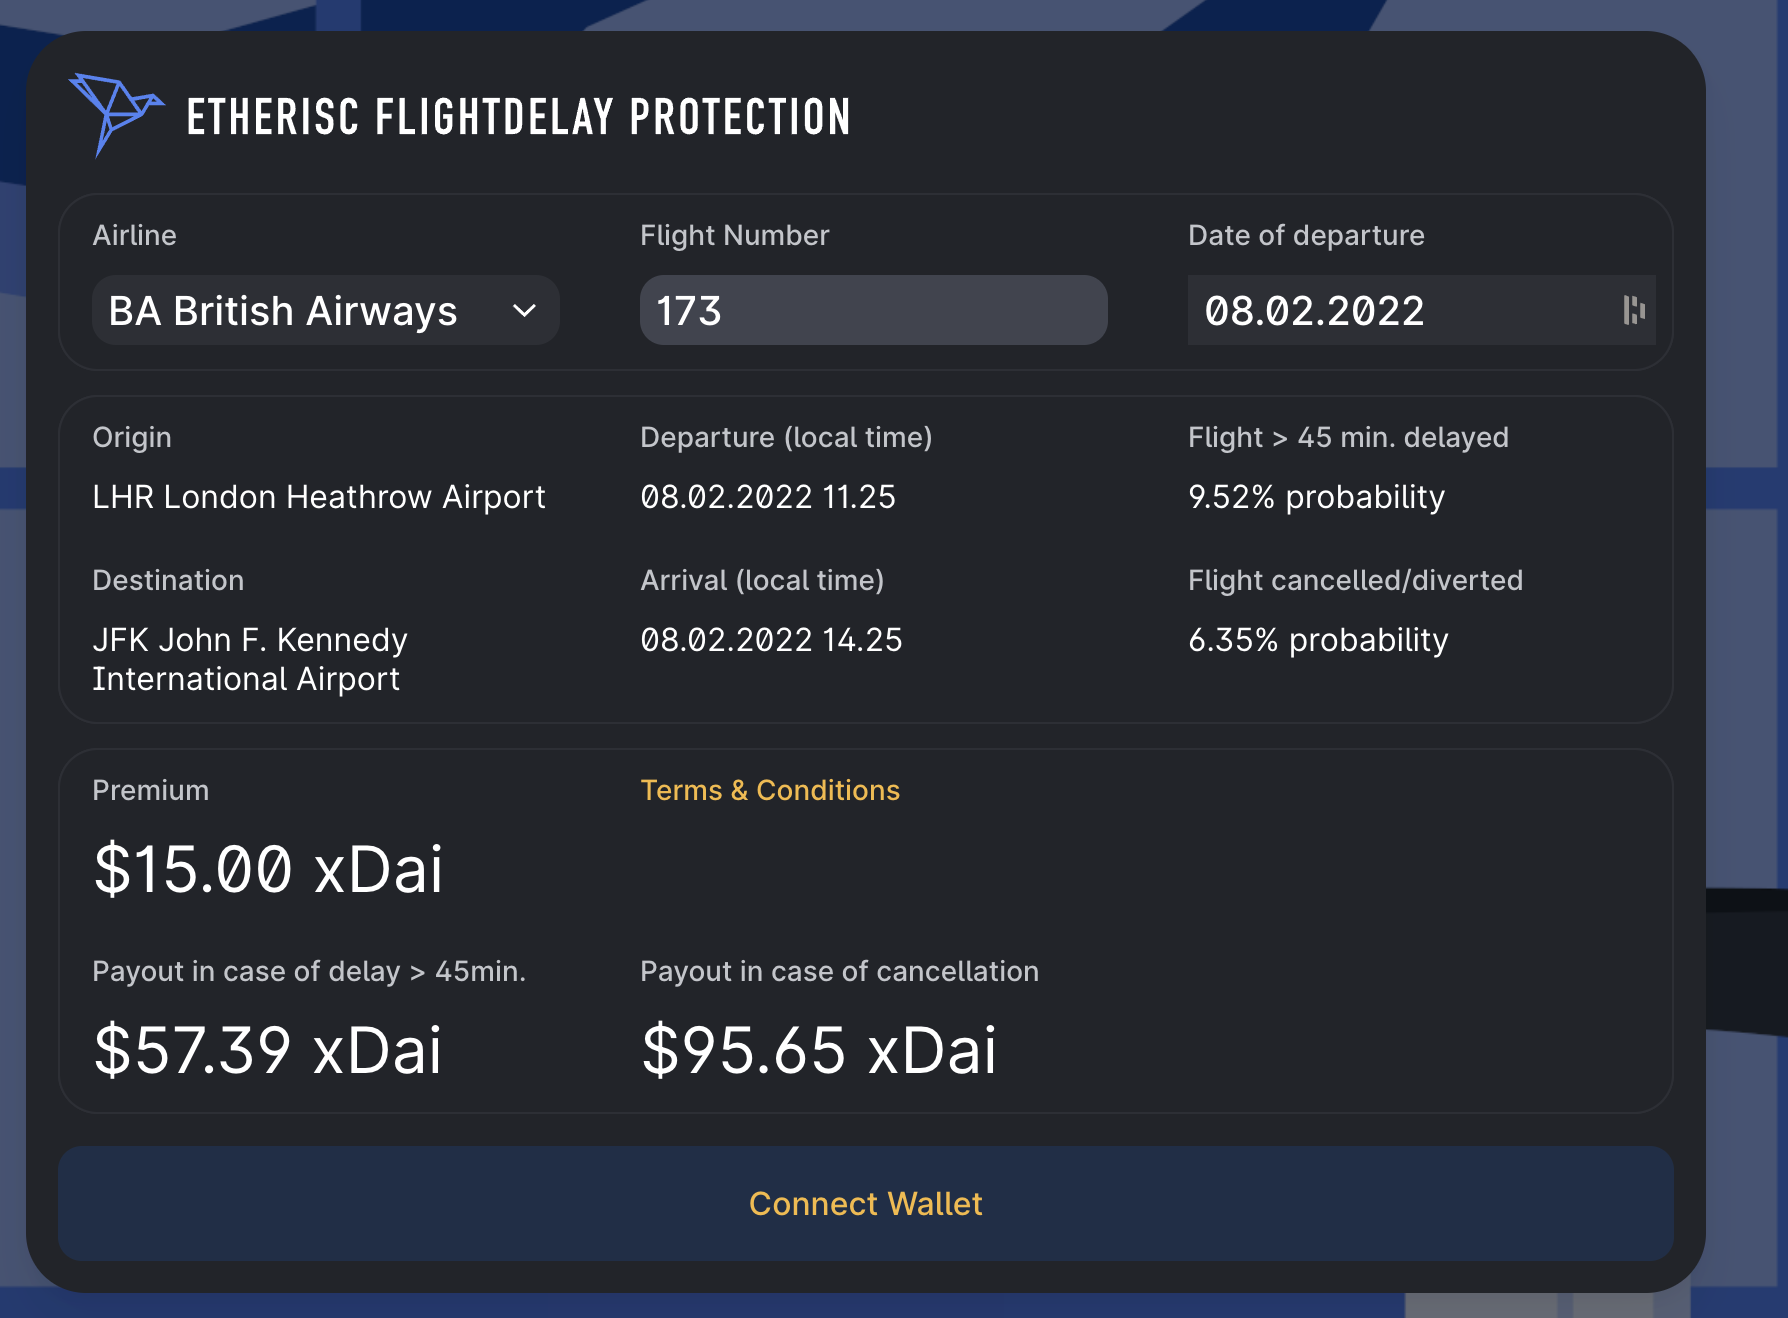
    A customer goes to Etherisc’s flight delay website to select airline, enter flight number and date of departure. The price is always the same, set at $15 and the payout varies according to the risk of the flight being delayed. Etherisc believes in transparency as it shoes the probability of the flight being delay in percentage terms and also the percentage of flights which have been cancelled in the last month along with the possible payout.

    The purchasing process happens when the customer links their MetaMask crypto wallet. No other details is required. No need to enter name, address, passport and no KYC because the $15 premium is below the threshold of when KYC is needed. In comparison to traditional insurers, there is no personal data that is stored by Etherisc, no paper work and the customer remains anonymous.

    If the flight is delayed or cancelled the payout happens automatically and the funds will be placed in the customer’s MetaMask wallet. No need for the customer to file a claim as in the case with traditional insurance.

    Chainlink

    A smart contract that lives on a blockchain has no direct connection to any external data source. For it to connect with external data you need an oracle as the ones provided by Chainlink. Insureblocks did a podcast with Sergey Nazarov, CEO of Chainlink. Chainlink provides to Etherisc decentralised networks of oracle data which is then aggregated into a single data file which can then be processed by Etherisc’s smart contracts.

    With Chainlink, Etherisc has access to an open data marketplace where it can select the relevant data sources such as FlightStats which has access to high quality data from all airports and all airlines.

    What’s next

    For the flight delay insurance, Etherisc is look for distribution partners such as travel agents as flight delay insurance needs to be integrated at the point of purchase.

    Etherisc is launching a platform for them to launch their own risk pools and are also forging a Global Alliance for Climate related risks.


    Ep. 175 – Coadjute – blockchain platform launch & mortgage stablecoins Jan 23, 2022
    Show notes

    In this podcast we had the pleasure of having Dan Salmons, CEO of Coadjute and John Reynolds, COO and founder of Coadjute return to Insureblocks to share with us the launch of their real estate blockchain platform and their thoughts on a mortgage stablecoin.

    What is blockchain?

    Dan’s definition of blockchain: In our previous podcast, Dan had used the glass box theory as an analogy to explain what is blockchain. For this podcast he uses a football match. In the old days before live TV existed, you had to rely on a newspaper reporter or a friend at a pub explaining to you what happened in a match that you had missed. In that scenario you have to rely and trust somebody else to share that information accurately and reliably to you. What blockchain does to the property market is that it introduces the possibility of live TV where you can form your own opinion as to what happened as can everybody else. Blockchain brings that sense of all its participants having the information for themselves without having to rely on some other intermediary to give them second hand information.

    John’s definition of blockchain: In August 2020, John saw blockchain as allowing the data to flow between the various different systems. Now for him, blockchain is fundamentally about trust. It’s the identity on the digital trust ecosystem that Coadjute has built by connecting numerous platforms and putting in a trusted identity. The data flows whilst important, can only be trusted if you know the identity of the source of the data. Digital identity and trust is fundamental.

    Who is Coadjute?

    Coadjute recognises that today the experience of buying and selling property in the UK, and in most other countries, is a complex and fragmented activity that takes a very long time, requires the coordination of a lot of parties and is overall a difficult, slow and frustrating experience for both the buyer and the seller.

    It’s the same for the people involved in the property market whether it is for the professions involved in legal, real estate, government, financial and son on. They all have to come together on a property transaction for it to work. Today there is no market infrastructure like the ones you find for the stock exchange and others.

    What Coadjute does is that it acts as a trusted network that connects all the systems of the different players in the property market in an interoperable manner. This means whether you’re a real estate agent, a legal conveyancer, a mortgage broker you can access your regular platform and yet still have access to the activities of the other parties involved in your transaction. You can see what is being done in real time, share messages, documents, identity funds and much more.

    Pilot launch

    The housing market in UK is composed of numerous parties ranging from legal firms, estate agents, and lenders to mortgage brokers. Today’s property process involves waiting for documentation, chasing for updates, rekeying data and endless uploading of documents, all of which add to the time and cost of the property transaction.

    With more than 25% of deals currently falling through and billions lost in efficiencies, Coadjute is introducing R3’s enterprise blockchain technology to help solve this problem.

    With the Coadjute network, there is greater transparency, a reduced risk of fraud and an accelerated process with significantly less admin. Conveyancers will be able to protect sensitive client data by Coadjute’s encrypted network, which only the conveyancer and the receiving party can see. In addition, all parties involved in a property deal – including the estate agent, conveyancer, mortgage lender, and broker – can track the live progress of the transaction from their existing software.

    Launching in July 2021, with the first live property deal on the network, a 3-bedroom house, Kent, Coadjute has ambitions to reduce the 5-month average process for buying and selling property by half.

    Seven of the most respected software companies in the property industry – including Osprey Approach, Redbrick Solutions and conveyancers AVRillo – have already signed up to the Coadjute network with the full backing of the Land Registry.

    There are over 100 software platforms in the UK property market who each have different APIs if they have an API. They all have different data models and data schemas. So for one of those platforms to connect to every other platform it’s an enormous job.

    With Coadjute, they connect to one platform they connect to many. Their users can then connect, interact and collaborate with users on all other platforms.

    Overall each software platforms that connect with Coadjute gets new features for their users, reduced connectivity backlog, and get to control their own data.

    Dan also commented that he was getting feedback from their participants on the network that they were getting closer to each other as if the simple fact of looking at the same data they seem to be getting better along with others on the network. Have you seen something similar to that on your own blockchain network? If yes please do add your comment onto this post.

    Top learnings

    The need to engage the ecosystem and the role blockchain can play in it. Coadjute has taken the view that blockchain is not a disruptive technology but a connecting technology. John’s advice is when you are looking to transform at the level of the market you really need to understand that market and its current software. Understanding how you can fit, complement and connect within that ecosystem is very important because blockchain is here to connect with it and add value to it.

    A mortgage stablecoin

    A “stablecoin” is a type of cryptocurrency whose value is pegged to another asset class, such as a fiat currency or gold, to stabilize its price. Today the purchase of a property has numerous different money flows between the conveyancer, lawyers, estate agent, mortgage lenders of the buyer and seller. In addition to payments to HMRC for stamp duty and a whole bunch of other sort of micro payments. All of these money movements are done over the CHAPS system without any kind of orchestrating application. These movements are done as push payments followed by an email or phone call confirming the transaction has been done, which in turn is followed by a number of reconciliation exercises between the parties.

    This creates high levels of administration which frequently cause last-minute delays in completion, and the familiar “Friday afternoon rush”. The traditional process is also vulnerable to fraud.

    The promise of a stable coin is that the lender could have a node on the network, they then capture the funds within the mortgage account, and they issue a token onto the ledger. That token can freely move around within the Coadjute network.

    The benefit of that is that the funds are staying locked securely with the bank, the tokens move around on ledger. Everyone has transparency and visibility of how the funds are being moved around. But the token itself is a claim on the actual mortgage funds that are sitting in the bank account.

    The party that then ends up with the token, such as the estate agent, ends up with a token for their portion of the of the sales fee, they can then redeem the token from the lending bank. What it does is it takes out a load of risk around push payment, fraud, it creates radical transparency, so everybody knows what’s going on.

    But a major benefit of this system is that you can programme the movement of tokens which enables 24/7 365 days a year, programmable property transactions that happen under a certain set of rules.

    New round of funding

    In December 2021, Coadjute raised a round of £6m from Praetura Ventures. The funds will be used for Coadjute to roll out its platform across the market. Dan shared that there has been a lot of interest abroad for Coadjute. The markets in which they are the most interested in are ones that have many of the same problems as the UK, being a highly fragmented market with a degree of digitisation and where there is a certain number of platforms for which Coadjute can connect with.

    ______________________________________________________________________________________________________

    This episode is brought to you by our friends and sponsors at R3. In this digital-first world, now more than ever, businesses need to modernize existing processes, systems and models – and enterprise blockchain provides the ideal solution for transacting directly and streamlining business operation.

    Developed by R3, Corda is light years ahead of other blockchain platforms in terms of privacy, security, scalability and interoperability. And–because Corda was built to meet the stringent requirements of highly-regulated industries, it can be used by firms of any type or size and in any industry.

    Blockchain applications built on Corda can reimagine and increase the potential of existing business networks, enabling direct and trusted transactions that eliminate friction and accelerate growth.

    Check out r3.com to find out more.


    Ep. 174 – R3 Product Vision: Market Trends & Needs and R3’s Long-Term Product Investment Jan 09, 2022
    Show notes

    Todd McDonald is the co-founder & Chief Strategy Officer at R3. In this podcast we discuss R3’s Product Vision and their views on market trends, market needs and R3’s long term product investment.

    What is blockchain?

    Blockchain is a way for multiple participants to join a network and update the state of that network without having to trust someone to coordinate amongst them. For businesses, Todd sees blockchain as a way to connect with more customers and more businesses without having to worry as much around the trust factor.

    Three market trends

    Back in September of this year Todd presented at CordaCon a presentation entitled “R3 Product Vision: Market Trends, Market Needs and R3’s Long-Term Product Investment.”In it he started by analysing three market trends:

    1. “Everything is an asset”,
    2. “push-pull of (de)centralisation”
    3. “Plan ahead for regulation”.

    Everything is an asset

    Blockchain has the ability to create digital scarcity. Essentially anything that you can prove ownership of can become an asset. Assets can be digitally mobile such as NFTs and/or they can be used as collateral for a loan.

    A digital asset of course can be the digital manifestation or representation of a real physical asset but equally it could also by a pure digital asset. Pure digital assets, such as the purchase of digital property in the Metaverse, have recently seen a bit of an explosive growth. Republic Realm purchased a $4.3 million 24×24 digital piece of land, whilst Metaverse Group in November made a $2.43 million purchase of parcels in Decentraland.

    Push-Pull of (de)centralisation

    Blockchains are custody and software. They’re the ability to custody digital assets in the software layer without having the need of human beings. Todd shared with us that some of the biggest investors in this space so far have been existing intermediaries. Financial market infrastructure is heavily investing in distributed systems and blockchain.

    He then explains what he sees as the different facets of the decentralisation journey:

    1. You need critical mass and become successful. There needs to be a journey to attract people to a network and distribute the roles of that network. Potentially over time the network can become more distributed to decentralised. What is interesting about the crypto side is that with tokenomics all participants can be incentivised from day one onto a decentralised network
    2. Progressive decentralisation a term coined by Jesse Walden, from Andreesen Horowitz, talks about starting out within a bootstrap minimum viable ecosystem, ie. quite centralised, which as it grows can progress into a decentralised one

    Plan ahead for regulation

    Once regulation starts it pretty much only increases. This comment isn’t specifically related to crypto regulation but more on financial services. There is an increasing amount of regulatory imperatives such as open banking, GDPR, and Central Securities Depository Regulation (CSDR).

    Modernising market infrastructure

    SIX digital exchange became live on the 18th of November 2021, when SIX, launched a CHF 150 million ($162 million) tokenised digital bond with Credit Suisse, UBS Investment Bank, and Zürcher Kantonalbank acting as the joint lead managers.

    What is interesting about this new digital market infrastructure that SIX launched off an R3 Enterprise Corda blockchainis that it leverages an existing ecosystem that SIX had. Second it has the ability to handle an asset through its lifecycle from cradle to grave. Three the settlement process, of settling into what is in effect into a central bank digital currency.

    What this illustrates is a way for these new tokenized assets to have higher velocity and to be able to reach across borders in a way that regulators are ok with.

    Corda & Conclave

    Early on it with the launch of Corda, it became clear that industries wanted to bootstrap networks where the founding participants wanted to control those networks.

    However, transactions and data need to be shared within networks but also across networks. Corda has been investing into interoperability overall. That applies to across Corda networks, and to legacy and emerging networks.

    With Corda there is a growing installed base of financial services. The question that arises is what is the ability for digital assets that live outside the regulated financial services. Is there a way for them to safely interoperate and take advantage of regulated digital ecosystems like an SDX who has the foundational bedrock for these digital assets on which to operate on?

    Conclave is about protecting data in use from prying eyes. It enables business to perform transactions that need to leverage data in a manner where they can still adhere to regulation on the data’s sovereignty. It’s about freeing businesses up from the knots that they potentially are tied in from regulation.

    Interoperability

    R3 is squarely focused on regulated networks. Todd mention that it’s interesting to see how crypto assets can be brought into an institutional setting, which is something that R3 is working on. There is a need for crypto assets to access settlement services which R3 can provide.

    Todd sees Corda as an incredibly compelling private side-chain for crypto networks.There could be a point where regulated assets could flow into permissionless systems such as Defi. Especially around the point of openness, programmability and identity.

    Across the crypto industry there is a trend towards openness. That however has to be balanced correctly with privacy. Openness is important as long as its accompanies with protection.

    Programmability another key factor has to accompanies with some form of safety. With programmability in environments such as DeFi, code is law. Transactions are fully automated. When errors happen either thought negligence or a misalignment of incentives you can have a problem which begs the question of the role regulation can take

    Identity can play a very important role, not necessarily in knowing the identity of all the participants but at least in knowing that the identity of a participant on the network has been validated.

    By bringing all these points together you can see how a regulated network can work in bringing in assets from these open networks to bring in a higher level of safety.

    R3 long term vision

    R3’s long term vision is incredibly focused on digital assets and digital currency and how those are safely issued, settled and traded. They are investing in the future of interoperability whether it is on the networks of networks and bridging the space to open networks and crypto.

    They will be focusing on their sandbox for digital currencies and investing in building tools and accelerators so that R3’s customers can more easily natively issue digital assets onto Corda and more easily tokenise arbitrary assets on Corda.

    About to release their Corda payments capability which will be able to integrate into existing payment service providers.

    Investing to facilitate the creation of asset network and for existing assets networks to integrate into existing payment rails so that over time to have on chain settlement via tokens or central bank digital currencies.

    Corda 5 will take the existing Corda and improve its scalability, security and performance for it to provide a market infrastructure that can last decades.

    ______________________________________________________________________________________________________

    This episode is brought to you by our friends and sponsors at R3. In this digital-first world, now more than ever, businesses need to modernize existing processes, systems and models – and enterprise blockchain provides the ideal solution for transacting directly and streamlining business operation.

    Developed by R3, Corda is light years ahead of other blockchain platforms in terms of privacy, security, scalability and interoperability. And–because Corda was built to meet the stringent requirements of highly-regulated industries, it can be used by firms of any type or size and in any industry.

    Blockchain applications built on Corda can reimagine and increase the potential of existing business networks, enabling direct and trusted transactions that eliminate friction and accelerate growth.

    Check out r3.com to find out more.


    Ep. 173 – Obscuro: a secret spell over DeFi Dec 12, 2021
    Show notes

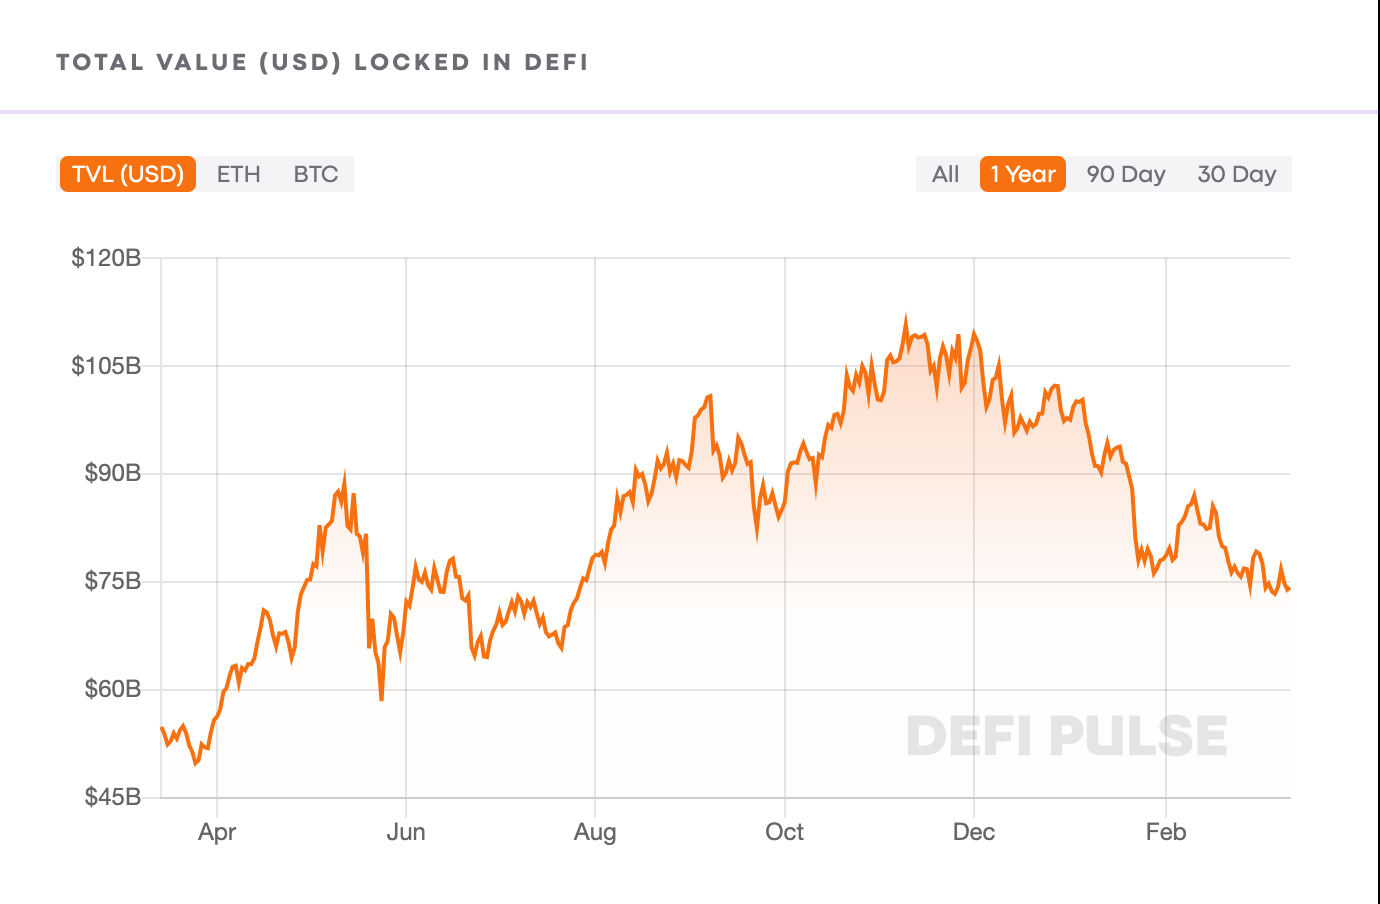
    Over the last 12 months Decentralised Finance also known as DeFi has really exploded with reported total value locked reaching $250bn. R3 who operates in the permissioned blockchain space is spinning out Obscuro into the permissionless space of DeFi. In this podcast we’re joined by James Carlyle who explains the DeFi landscape, the challenges it faces in terms of privacy and scalability and how Obscuro can address these.

    What is blockchain?

    Blockchain is a distributed databased. Instead of one party running it, it is run as a network by a group of entities who don’t necessarily trust each other. It contains features that ensure that entities don’t need to trust each other, they can trust the infrastructure and the code itself.

    James has been on a blockchain journey since 2015 when he started off with permissionless public systems like Bitcoin and Ethereum prior to joining R3 in 2015 and helping to design Corda. Corda though had a very different principles than permissionless public systems as it was designed as a permissioned blockchain. The participants all have a verified identity so you know who you are dealing with, whilst on permissionless system they have a pseudonym. Now with Obscuro, James is returning to permissionless public systems.

    Decentralised finance (DeFi)

    Over the last 12 months Decentralised Finance also known as DeFi has really exploded. A few weeks ago JP Morgan reports that total value locked (TVL) has grown from last year’s $20bn to $200bn today.

    For James, Defi is an expression of freedom and of innovation. It’s growing very rapidly as it’s able to innovate at lightspeed. All of these applications are open source which means that it is possible to take an existing idea to either build upon it or in some cases to steal it and simply rebrand it. These things increase the level of innovation and increase the level of take up.

    At the heart of DeFi is transparency. It runs on permissionless systems, which means anyone can take part, download the data and help in the validation process.

    The first generation of DeFi builders and users were not interested in privacy and James believes that DeFi is heading towards a new generation to builders and users who are aiming for a more mass market where privacy is important. The ECB released a report on the digital Euro where privacy is seen as a key digital enabler.

    Whilst privacy is important it can unfortunately also be used as a cloak for illegal behaviour. For DeFi to be picked up and used by the mass market it has to be more regulated. Regulation needs identity and KYC. R3 is uniquely placed to interact in this space as it has this rich heritage of having very strong ties with regulation and regulators

    Miner extractable value (MEV)

    In a public blockchain system such as Ethereum there are participants who are submitting transactions. Miners who are here to confirm transactions can see the contents of the transactions that users have submitted. They can take advantage of it in some cases in what is called front running. For example, if you want to buy something on the market you don’t want someone else to bid the price up ahead of the transaction. That’s what is possible when a miner can spot that a user is trying to something and they decide to step in first and thus get the transaction before the user and the user is left behind buying it at a higher price.

    It has been estimated that around $1.4 billion of MEV is being taken from Ethereum blockchain users annually from a total DeFi market of around $50 billion. Global financial markets are worth $100 trillion. One of the main motivations of Obscuro is to help solve some of these issues.

    Ethereum scalability issues

    Ethereum to some extent is a victim of its own success as it suffers from scalability issues. With the explosion of DeFi projects, and their corresponding transactions that need to be processed by all of the nodes on the Ethereum network, that has created a bottleneck issue where people have to bid more to have their transactions processed.

    The fees to process the transactions can start to rise very rapidly where whilst it may not be felt so much for low value transactions but for a newly minted NFT piece of art the fees can go very high.

    To address this issue other layer 1 networks (L1) like Ethereum, such as Solana, Cardano or Avalanche who reduce the number of validators in the work, or require the validators to run more powerful hardware.

    Another approach is to use the L1 as a record keeping layer where the transactions won’t actually be processed but will instead be processed on a second network (L2) and where periodically the transactions from L2 will be recorded onto the L1.

    Obscuro

    Obscuro, whose origin is Portuguese means “obscure” in English. For James and his team they chose Obscuro due to Harry Porter as it was the incantation of a charm used to conjure a blindfold over the eyes of the victim, therefore obstructing their view of their surroundings.

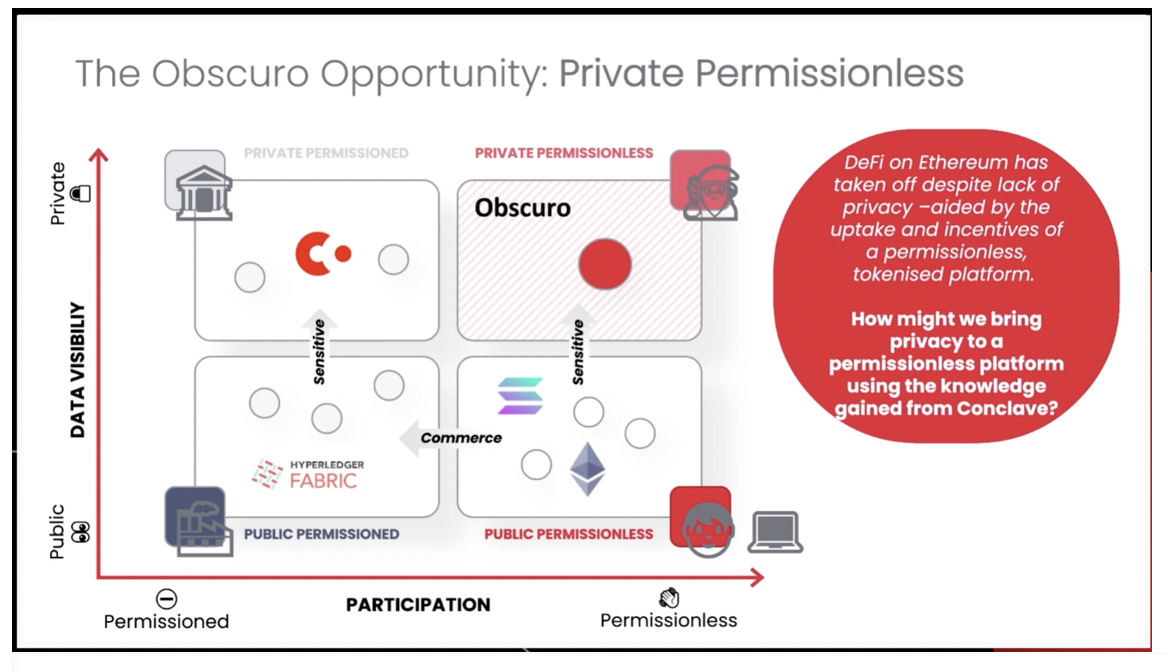
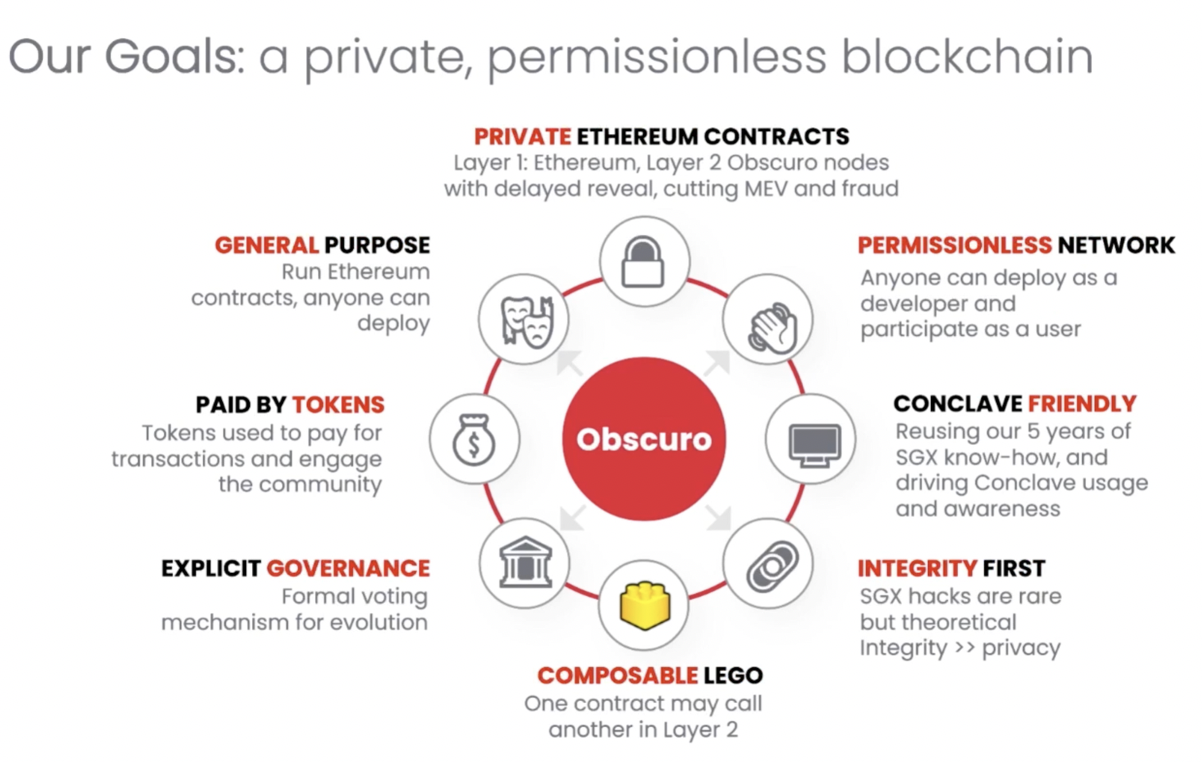
    The objective of Obscuro is to provide confidential, smart contract execution.

    Obscuro, source R3 opportunity

    It means that until now applications that may have been deployed directly onto an Ethereum distributed application or deployed onto an L2 network, they can now be deployed onto an Obscuro network. The contents of those contracts would remain secret and hidden from users.

    A users’ wallet encrypts the transaction and sends it to an Obscuro node on the Obscuro network. Only the Obscuro nodes themselves can understand the transaction. The transactions interact with contracts that have been deployed onto the Obscuro network and the contents of all of those contracts is also encrypted. The Obscuro network is a group of nodes that works within a gossip network, a peer to peer permissionless network.

    And it’s encrypted so that only the obscure nodes themselves can understand the transaction. And the transaction interacts with contracts that have been deployed onto the obscure network. And the contents of all of those contracts is also encrypted.

    The network processes the transaction and updates the state of the contract. To illustrate this, James provided us with an example of an auction. In an auction on Ethereum everyone can see all of the bids, they can see the addresses of the bidders and the bidding patterns. An auction contract deployed onto the Obscuro network would be hidden. It’s effectively a sealed auction with sealed bids. No one can see other bids. The bids themselves have been encrypted and the linkage of the bid to an identity is also hidden. Privacy is thus achieved for users. Whilst privacy is achieved it isn’t an ultimate form of privacy as if necessary law enforcement bodies can take action against those who would use Obscuro for illegal actions.

    One of the design goals of James’ team is that standard Ethereum contracts can be deployed onto the Ethereum contract without changing it.

    Obscuro, source R3

    Incentives and governance

    There are a set of economic incentives for people to participate in the network whether they are users or aggregators. Users get some personal benefit from transacting within these contracts whilst aggregators need to be rewarded for running infrastructure. These rewards will be some form of utility token.

    James expect that they will set up a decentralised autonomous organisation to govern this network.

    Obscuro’s relationship with R3

    Obscuro isn’t part of R3’s core business. R3’s core business is trust technology for regulated industries. Whilst the work being done at Obscuro might be very beneficial for regulated industries it isn’t aimed solely at regulated industries. Obscuro is likely to be spun out of R3. However it could actually drive utilisation and interest in R3’s confidential computing product called Conclave.


    Ep. 172 – Confidential computing tackling human trafficking – insights from Hope for Justice Dec 05, 2021
    Show notes

    Tim Nelson is the CEO of Hope for Justice and is part of the founding board of the charity which exists to try and end all forms of human trafficking and modern slavery across the globe. They work alongside major multinational businesses through an organisation called the Slave Free Alliance that they set up a few years ago.

    What is blockchain?

    Blockchain is a distributed database that is shared between the nodes of computer. It stores information electronically in a digital format. It maintains a secure and decentralised record of transactions and what differentiates it to other databases is that it guarantees the fidelity and security of a record. This generates trust without the need of a third party.

    Modern Slavery

    According to the International Labour Organisation (ILO) there are 40.3 million people in forced labour, sexual exploitation, domestic servitude, organ harvesting and forced marriage worldwide:

    • Including 24.9 million in forced labour and 4 million in forced marriage.
    • It means there are 4 victims of modern slavery for every 1,000 peoplein the world
    • 1 in 4 victims of modern slavery are children.
    • Out of the 9 millionpeople trapped in forced labour, 16 million people are exploited in the private sector such as domestic work, construction or agriculture; 4.8 million persons in forced sexual exploitation, and 4 million persons in forced labour imposed by state authorities.
    • Women and girls are disproportionately affectedby forced labour, accounting for 99% of victims in the commercial sex industry, and 58% in other sectors
    Global Estimates of Modern Slavery

    Most people think that slavery was ended with the William Wilberforce Day. However every day around the world people are being trafficked every day. They are forced to work within the supply chains of major multinational businesses, into all forms of sexual exploitation, into forced domestic servitude and in countries where there is no organ donation scheme, there is organ harvesting.

    Most people are shocked to know that for example in the UK, the number one place people are trafficked to the UK is actually from the UK. People are actually taken in the UK.

    When Hope for Justice started doing rescue and investigation in the UK, the organisation started in an area in West Yorkshire that covers 2.2m people. At that time the entire police force across England and Wales had rescued 88 individuals and said that was the extent of it through an operation called Pentameter one. Hope for Justice within its first year of operation in just West Yorkshire alone, rescued 110 victims of which the youngest was just three months old trafficked for sexual exploitation and the oldest was 58 years old for forced labour.

    Impact of COVID

    The impact of COVID has been massive on everyone around the world. The shutting down has made a bigger impact on the most vulnerable in the world. Farmers have missed crop planting or harvesting whilst others haven’t been able to go to work putting them into a very vulnerable situation. It is in that backdrop that we see a real shift happening. Companies have rolled back efforts the they were doing globally. According to Tim, COVID has probably hit back the movement against modern slavery about 10 – 15 years.

    The vulnerabilities that existed in communities have been exasperated by COVID and one where traffickers have gone in to exploit those individuals who have the greatest degree of vulnerability. The degree of this impact is going to be felt for the decades to come as individuals who have had to take on debt, many of them are going to become debt bonded to the individual traffickers themselves. Whilst those who have taken loans whose interest rate is so high that the will never be able to pay off those loans. There is a quarry in India where 30,000 families are debt bonded to the quarry.

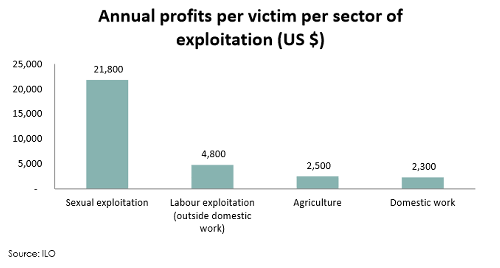
    A $150 billion industry

    According to the International Labour Organisation (ILO) forced labour generates annual profits of US $150 billion. This makes it the second most profitable, serious and organised crime in the world after drug trafficking. What traffickers say is “if I sell a kilo of heroin, I can only sell at once. But if I can have a person who’s enslaved, I can have them held for years.” To compound this issue Tim believes less than 1% that is being spent against drug trafficking is being spent on stopping human trafficking.

    Tim gives the example of a Filipino lady in Los Angeles that was held for 33 years as a domestic slave forced to sleep in a garage and now allowed to leave the house.

    There’s roughly 20,000 individuals who are working every day on human trafficking, globally. The majority of those organisations sit in the aftercare space or the awareness space. As a result, the response doesn’t meet the problem. From a UK perspective, last year, there were 10,613 individuals, people who presented the signs of being a traffic of victim, who were entered into the national referral mechanism. For Tim, the challenge for what they’re doing is how can they use technology to help augment the work their doing so that it amplifies and magnifies the impact that they’re making.

    The Slave Free Alliance

    The UN SDG 8.7 has set the goal of ending slavery in the supply chains of major multinationals. Hope for Justice realised that a number of individuals they were rescuing where from the supply chains of businesses. Hope for Justice worked with Accenture who helped them to productize what they were doing and helped them to set up the Slave Free Alliance in 2018.

    Businesses are invited to join a membership scheme where they are given access to the support and services from the Slave Free Alliance. Slave-Free Alliance offers a wide range of services and access to its experts, including training, gap analysis, due diligence, risk management resources, and help with investigations, crisis response, remediation and Slavery and Human Trafficking Statements

    Within the last 3 years they have signed up 95 major multinationals and are planning to launch in the US, Norway and Australia by the end of 2021.

    Battery

    Whether it’s in your mobile phone, laptop or electric car, most batteries today are produced using cobalt of which 70% would have originated from mines in the Democratic Republic of Congo. These are mines are mined by children and or forced labour.

    The Paris Accord has set for the increase electrification of cars by car manufacturers. However, to achieve that objective in just Europe and the US would require a 30 times increase in production of cobalt mining for that to happen.

    Using confidential computing to fight human trafficking

    Tim explains that it’s not until you look at the data that you can start to draw correlations to what needs to happen. There was a clear need to start using data and AI to drive up intelligence that can help the organisation to make the right decision.

    An example would be to start pulling information together from various countries to identify a particular type of person that is more susceptible to being trafficked. This can help create red flags Border Force officials to look out for a certain type of person of a certain age that is more susceptible to human trafficking.

    It also helps to identify regions that are more susceptible to human trafficking for example in the case of one particular country up to 95% of all victims were coming from within 35 miles of one city.

    The hope is to build a blockchain solution that will enable them to have a database that would benefit many industries for there to be a clear a clear understanding of who the good and bad actors are in a particular area. The key point is that when a supplier within a supply chain is identified that industry players don’t just walk away from the supplier but actually try and drive change. Because, if you walk away from that supplier, it doesn’t actually stop it from happening. Whereas if you go back to the supplier and offer to bring real systemic change to that supplier then change is possible.

    R3’s Corda blockchain

    In terms of identifying a blockchain for Hope for Justice and the Slave Free Alliance’s requirements, Tim’s team chose R3’s Corda as it provided the combination of safety and security they needed. A lot of the trafficked victim’s data that is being stored is very sensitive. As it carries their location but also these are individuals who could potentially form part of court cases, both on civil and criminal litigation.

    By having a combination of both Corda and Conclave it provided them with the double level of security and safety that they required.

    Plans for the future

    In 2020, they have helped 18,110 individuals find freedom. In terms of their plans for the future, they aim to open up another set of operational investigating hubs in the UK, expand in more states in the US and to expand into other countries so that they can operate out of every continent across the globe.

    How can you help?

    Readers and listeners of Insureblocks can help Tim and his team in three ways: time, treasure and talent.

    • If you have a core skill and the time to support Hope for Justice head over to their website and tell them how you’d like to help.
    • Firms have CSR budgets, some give financially directly to charity, some give via fundraising events. Individuals can also donate money for example if costs roughly $500 to see an individual child taken from exploitation, given trauma informed care, catch up education, medical care, clothing and food, looked after for a period and then reintegrate them with their families or foster families and were not appropriate look after them for up to 2 years in that process.

    A few years ago, a 14 year old girl raised $65,000 by walking 300 miles.

    To donate your time and talent to Hope for Justice: https://hopeforjustice.org/

    To donate treasure: https://hopeforjustice.org/donate/uk/

    _______________________________________________________________________________________________________

    This episode is brought to you by our friends and sponsors at R3. In this digital-first world, now more than ever, businesses need to modernize existing processes, systems and models – and enterprise blockchain provides the ideal solution for transacting directly and streamlining business operation.

    Developed by R3, Corda is light years ahead of other blockchain platforms in terms of privacy, security, scalability and interoperability. And–because Corda was built to meet the stringent requirements of highly-regulated industries, it can be used by firms of any type or size and in any industry.

    Blockchain applications built on Corda can reimagine and increase the potential of existing business networks, enabling direct and trusted transactions that eliminate friction and accelerate growth.

    Check out r3.com to find out more.


    Ep. 171 – Exploring CBDCs – insights from the Bank for International Settlements Nov 21, 2021
    Show notes

    Central bank digital currencies (CBDCs) are increasingly being talked about in the press with announcements of initiatives from different central banks working on CBDCs coming out left right and centre. Few however are as forward thinking and embracing a collaborative approach as the Bank for International Settlements (BIS). For this podcast we are joined by Daniel Eidan, Adviser and Solution Architect at the Bank for International Settlements (BIS) in the Innovation Hub where he builds technology solutions for the central banking community with a special focus on blockchain and CBDC. He will share with us some of the exciting work his team are doing for driving CBDC forward.

    What is blockchain?

    Blockchain and DLT is often referred to as Web 3.0 whilst the internet of today is Web 2.0.

    Web 2.0 enables to globally connect communications protocol whilst blockchain and Web 3.0 isn’t just about putting communication protocols digitally but to store value digitally. What blockchain enables is to execute computations between different members and keep a record of state. Essentially as Daniel mentions we can encapsulate value. Value can be cryptocurrencies, central bank digital currencies, contracts and many other forms of value. This wasn’t something possible in the Web 2.0 because the fundamentals weren’t there.

    What are CBDCs?

    To fully understand what CBDCs, central bank digital currency, are you first need to understand what is a currency. Money and currency in general have three attributes:

    • They are a unit of account
    • A store of value
    • A medium of exchange

    What central bank digital currencies do is that they digitise those three attributes.
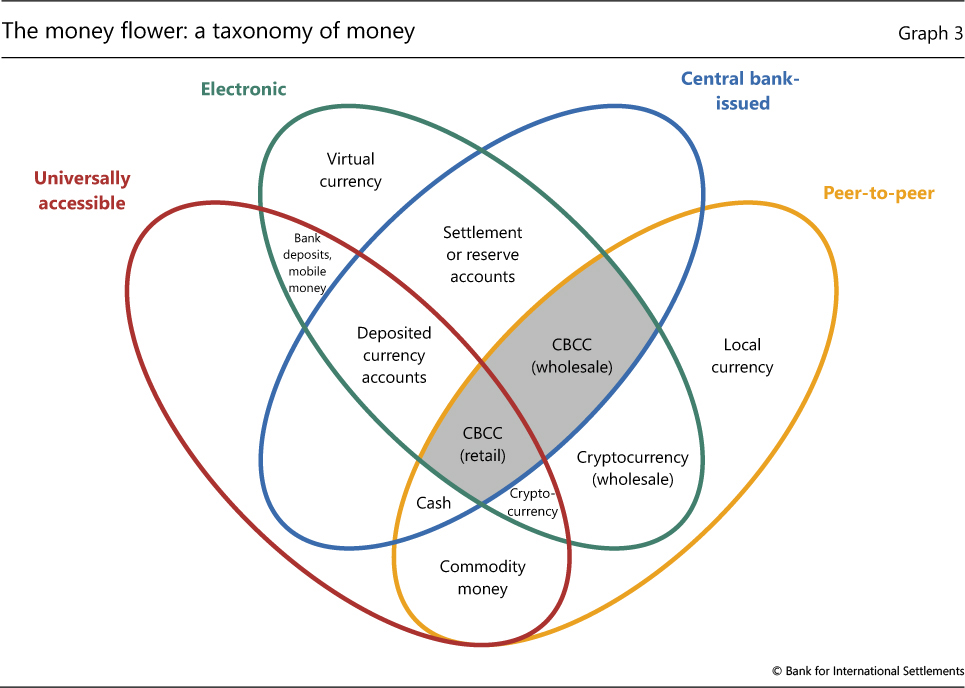
    To explain how this happens Daniel uses the “money flower” approach which looks at its four different attributes:

    • Is it universally accessible?
    • Is it electronic?
    • Is it issued by a central bank?
    • Is it moved around in a peer to peer way?

    A retail form of CBDC will have all four of the money flower attributes. It will be universally accessible, it will be electronic, it will be issued by a central bank and contain central bank liability, and it will transact in a peer to peer way.

    What is important to recognise is that most of the retail monetary base is not central bank money, it’s commercial bank money. For example, when you deposit money at you bank it is likely that a large part of your fiat currency is with a claim against your commercial bank. Then through a set of mechanisms that claim is insured by potentially a central bank or a federal institution.

    The only claim that retail can have against a central bank is in the form of cash. Cash of course is a tiny percentage of the total amount of money individuals have. What CBDC does is takes that cash liability, in a retail context, to exist in a digital context in a way that’s accessible to anyone.

    The question is what happens to individuals who do not have a smart device, or electricity, or WIFI? In addition, how is universal accessibility attained to individuals with disability issues or are elderly? There are a number of technical solutions that can help to lower this barrier but it is one that is a challenge in terms of the last mile for reaching ubiquitous CBDC.

    In the case of wholesale, the case for CBDCs is to broaden the base of digital currency from tier one institutions that are regulated domestically to fintechs, startups and perhaps banks in other jurisdictions. So, it’s really extending the promise and the capability of central bank money.

    Privacy

    Why is cash private? There isn’t actually a mandate for money to be private. The fact that cash is private is a consequence of the technology. Cash however isn’t always private. For example, purchasing a house in only cash cannot be done in a private privacy manner.

    Daniel makes the important point that CBDC will promote more privacy than digital payments of today that are motivated by commercial interests. Daniel then asks “would you be more comfortable just in terms of that privacy aspect to pay with your Visa card, knowing that visa has your data and visa can do whatever they want with your data, as long as it falls within they’re licence as a payment provider versus, something that’s issued by a central bank that the central bank has no other objective other than what’s best for the social good.”

    Bank for International Settlements (BIS)

    The Bank for International Settlements (BIS)’s mission is to support central banks’ pursuit of monetary and financial stability through international cooperation, and to act as a bank for central banks. As individual’s lives are increasingly becoming more digital and it is increasingly apparent that any central bank whose aim it so provide financial stability has to invest in the digital space. In 2019 the BIS launched the Innovation Hub Network, to support the Innovation Hub priorities, share knowledge about technology projects and discuss innovative answers to problem statements relevant to central banks.

    The Innovation Hub Network is a joint partnership between the BIS and regional central banks to open innovation hubs that service the central banks their surrounding regions. The first three were in Switzerland, Hong Kong and Singapore. Now there are new hubs in London, Stockholm, Toronto and a strategic partnership has been set up with the New York Fed. They’re also planning to open hubs in Frankfurt and in Paris amongst many others.

    These hubs are going to engage the private sector to bring technical talent and know how to inform policy markets and the central banking community.

    CBDC is one of the six verticals that the Innovation Hub Network is working on: supervisory and regulatory technology, next generation financial market infrastructures, open finance, cybersecurity protocols and on green finance.

    Project Inthanon-LionRock to mBridge

    In May 2019 the Hong Kong Monetary Authority (HKMA) and the Bank of Thailand (BOT) launched Project Inthanon-LionRock a first common platform for multiple CBDC settlement. Phase 1 of this project achieved a PoC built on R3’s Corda designed to allow the participants of each network to conduct fund transfers and foreign exchange transactions on a peer-to-peer basis, thus reducing settlement layers.

    Phase 2 of this project was built by ConsenSys on Hyperledger Besu to extend Phase 1 to two other jurisdictions being the Digital Currency Institute (DCI) of the People’s Bank of China (PBC) and the Central Bank of the United Arab Emirates (CBUAE). The participating central banks are able to control the flow of their CBDC on the prototype, monitor transactions and balances of their issued CBDC, utilise programmable levels of transaction privacy, and automate certain compliance functions.

    The project then evolved to Phase 3 called mCBDC Bridge, “m” for multiople, or in short mBridge. As the name implies the platform is built to facilitate multiple different central digital currencies to perform cross border payments in a cheaper, faster and more efficient manner.

    Today is obvious that there is no public sector organisation that has the mandate to facilitate cross border payments. It is all provided by private institutions who are commercially driven. The amount charged will depend on locations, currency pairs and the amount of money being sent. Currency pairs for example that do not have a lot liquidity may have to go through a third currency pair to facilitate the transaction leading the user to have to pay 2 FX rates. This contributes to the reason on why remittances can cost 6.5% of fees on the transaction.

    With mBridge there is the opportunity to provide a faster, better and cheaper way settling payments in central bank money. Transactions for example have moved from a few days to within two seconds!

    mBridge looks to drive the use case around international trade settlements to facilitate international trade between those jurisdictions and also to open up the platform to additional central banks and also to private sector players.

    Inthanon-LionRock to mBridge

    Electronic Hong Kong Dollar (e-HKD)

    e-HKD is a joint partnership between The Hong Kong Monetary Authority (HKMA) and the BIS Innovation Hub is an attempt at exploring retail CBDC. Retail CBDC is very much about the last mile solutions. It’s about the privacy, offline, how the retail space interplays with the wholesale space and how this doesn’t influence the role of commercial banks in the economy.

    In September a whitepaper was published entitled “e-HKD a technical perspective” that explores potential architectures and design options that could be applied to the construction of the infrastructure for distributing e-HKD, and reports the initial thoughts and findings. Specifically, it aims to explore technology solutions that address the problems of cross-ledger synchronisation, over-issuance prevention, privacy-preserving transaction traceability, and flexible instantiations of different two-tier distributions models.

    e-HKD_A_technical_perspective

    The paper displays the focal point on how money moves between two interoperable systems, one being the wholesale monetary base and the second a retail monetary base with a special focus on privacy.

    7 Central Banks exploring retail CBDCs

    Bank of Canada, Bank of England, Bank of Japan, European Central Bank, Federal Reserve, Sveriges Riksbank, Swiss National Bank and BIS have joined forces to explore what a retail CBDC might look like.

    BIS - CBDC

    In their 1st report, the banks got together to create some baselines for the thinking around retail CBDC. In September 2021 a new report was published that had three categories:

    • systems design and interoperability. As central banks operate within a domestic agenda, the piece of interoperability is critical to ensure that they can connect to each other
    • user needs and adoption
    • financial stability implications

    _______________________________________________________________________________________________________
    This episode is brought to you by our friends and sponsors at R3. In this digital-first world, now more than ever, businesses need to modernize existing processes, systems and models – and enterprise blockchain provides the ideal solution for transacting directly and streamlining business operation.

    Developed by R3, Corda is light years ahead of other blockchain platforms in terms of privacy, security, scalability and interoperability. And–because Corda was built to meet the stringent requirements of highly-regulated industries, it can be used by firms of any type or size and in any industry.

    Blockchain applications built on Corda can reimagine and increase the potential of existing business networks, enabling direct and trusted transactions that eliminate friction and accelerate growth.

    Check out r3.com to find out more.


    Ep. 170 – Leveraging Mastercard’s DNA onto blockchain – Mastercard Provenance Solution Sep 19, 2021
    Show notes

    Leandro Nunes, Vice President, Product Development and Innovation at Mastercard, joins us to share how he leveraged Mastercard’s DNA in scalability, payment automation and governance. We also discuss the important of a data governance model and his top tips for building scalable blockchain solutions.

    What is blockchain?

    Blockchain is a distributed ledger technology (DLT) that uses a consensus methodology to immutably record blocks in sequence in a ledger. It’s a technology that is driven by data governance. The governance is on the data side not necessarily on the blockchain. Data governance looks at the question of ownership of the data, who has visibility over it and the rights for sharing it.

    It allows for the creation of networks to tackle use cases where the participants can integrate their systems in a decentralised environment where they can share the data. This provides the visibility to increase the trust between the participants.

    Leandro also stresses what blockchain is not. It’s not the saviour of the world and shouldn’t be a solution looking for a problem. As any other technology blockchain needs to connect and be integrated with other solutions such as AI, IoT, payments and others.

    Mastercard’s DNA – network builder

    When talking about blockchain there is this dependency on how to build and manage a network for different participants. In some ways these challenges are similar to the one of payment networks like Mastercard who has the established the credibility of having the global coverage, the need to scale, and acts as a neutral network builder not taking any sides. It is this element which is within their DNA. It is this DNA which can be leverage to build and gain adoption to new technologies such as blockchain.

    When you swipe your Mastercard within two seconds the user gets an approved message. Within those two seconds a lot of things happens amongst many participants to make sure the settlement is done.

    Mastercard provenance solution

    Mastercard’s Provenance Solution, is essentially an API layer on top of a Mastercard blockchain that serves as an orchestration hub for an entire ecosystem of partners. It bridges the supply chain traceability events with a payments network. This enables to share supply chain related data to inform the decision making process for the payment side. Decisions can be automated which in turn reduces the reconciliation costs, dispute resolution and speeds up the entire process.

    Leandro stressed that they’re not a tech company trying to sell blockchain. They use blockchain as a technology, the value they can bring in addition to combining supply chain traceability along with the payment side is around bringing scalability to the governance. Working with their partners to answer the questions of how do you build a network where you can be neutral within its governance structure? How do you create a governance where you don’t take sides?

    Use case: Australian farmers

    In August 2021, Cirralto, the B2B payment services business, announced it is leveraging the Mastercard Provenance Solution, and the Fresh Supply Co digital supply chain network, to provide Australia’s farmers with better access to trade finance.

    The WTO estimates between 80% and 90% of global trade relies on trade finance, yet there is a $1.5 trillion gap between the market demand and supply for trade finance. Financial institutions usually don’t want to lend money to a small supply chain company that they don’t know. However when you bring traceability, you bring blockchain and you increase visibility and trust these financial institutions realise they can use this data to reduce their risk assessment to make better lending decisions.

    Cirralto brings the fintech side, along with local lenders in Australia, to Fresh Supply Co supply chain network who brings the traceability platform and sharing the data with the Mastercard provenance solution. Through enhanced supply chain insight, financial institutions leverage data-driven credit decisions to drive lending confidence and increase trade finance opportunities for farmers.

    Exporters can now know exactly what they’re receiving from the growers. They can keep their payment terms of 30 – 45 days to pay the growers, however the growers can access discounted invoice pay where they can get paid within 48 hours.

    The buyer knows exactly what’s going on and doesn’t need to spend a lot of money on the reconciliation process. The growers have much more confidence they are going to get paid for what they have delivered and they get paid sooner than usual thus increasing their cash flow.

    Networks of networks

    During COVID Mastercard made an announcement with AON to introduce a new solution to provide supply chain protection for global Covid-19 vaccine shipments.

    The solution provides transparent cargo insurance coverage for Covid-19 vaccines by combining sensor data and analytics. The offering enhances all risk marine cargo insurance with timely payment for doses that fall outside of the agreed-upon temperature range while being transported or stored, enabling more effective risk management and claims support. Real-time reporting of any temperature deviation will also provide for the mitigation of losses and help maximize the number of doses that are administered to the public.

    The solution initially started through the partnership between Mastercard Provenance Solution and ChronosCloud alongside DW Morgan partnered to connect all partners of the supply chain with real-time IoT sensors for active condition monitoring. At this point they realised the opportunity existed not just to use supply chain data for payments but also for insurance thus bringing on AON and demonstrating the opportunity for networks of networks

    Use case: Zimbabwe – cattle traceability system

    In 2018, 50,000 cattle in Zimbabwe died because of a tick-borne disease.

    The lack of a traceability system has seen Zimbabwe unable to export beef to lucrative markets in Europe and the Middle East, reducing export earnings from beef to the tune of $50m due to sanctions. The government of Zimbabwe had the challenge to resolve this issue.

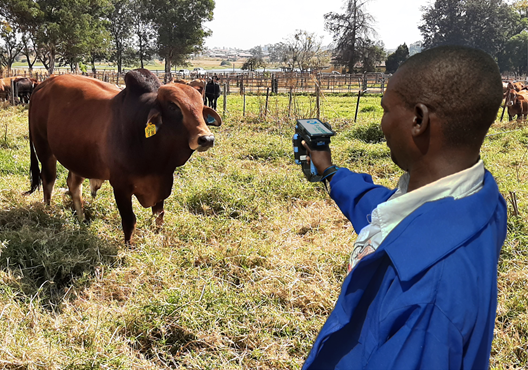
    E-Livestock Global solution brings end-to-end visibility to the cattle supply chain. Commercial farmers and dipping officers tag each head of cattle with a unique, ultra-high frequency RFID tag – as mandated by the Ministry of Agriculture – and register it and its owner onto the solution. Each time the animal gets dipped, vaccinated or receives medical treatment, the tag records the event onto the traceability system.

    Leveraging Mastercard Provenance Solution, E-Livestock Global records these events to maintain a secure and tamper-proof trail of each animal’s history. This, in turn, supports the entire supply chain with trusted, transparent and verifiable data. For farmers, it provides an irrefutable record that proves ownership, supports sales and exports, as well as allows them to obtain a loan, using their cattle as collateral. For buyers, it enables them to efficiently manage their operations and guarantee product quality to their customers.

    Coming back to the point about networks of networks is how this solution can enable to provide financial inclusion to the farmers in Zimbabwe by providing them with a digital wallet. It also opens up the opportunity for an insurance company to leverage the data and offer parametric insurance.

    Use case: GrainChain

    In October 2020, Mastercard announced a collaboration with GrainChain, a technology company that enables supply chain visibility, empowering suppliers and farmers while reducing risks to buyers in the United States, Mexico and Central America. GrainChain tracks over 24 commodities in four different countries.

    Together with GrainChain, Mastercard Provenance Solution delivers end-to-end visibility throughout the supply chain, allowing participants to forensically track commodities, from the initial inputs and raw materials to harvesting and processing to logistics and delivery to the consumer’s hands. Doing so enables brands and producers to proactively protect consumers and manage their brand reputation, business efficiencies and bottom line.

    The increase visibility enables farmers to get access to finance and also to cheaper finance as the platform can demonstrate the payment guarantees farmers get from the traders.

    Key learnings for building scalable solutions

    Having worked on a number of use cases with Mastercard across industries Leandro has the following key learnings he shared on Insureblocks:

    • Build a business incentive model where the participants see the benefit for adopting the solution. It cannot be a big brand mandating them to come on board
    • Understanding capacity of the participants. They may not have the resources to allocate for a new project
    • Bring other assets that can enhance the core solution

    Use case: Seafood traceability system

    Consumers increasingly want to know the story behind the food that they consume–the source of the produce, meats and seafood, and their journey to the table. In October 2019 Mastercard announced a partnership with Envisible, a supply chain visibility in food systems company, to launch a pilot with the largest United States food co-operative Topco Associates and the supermarket chain Food City for its seafood inventory.

    Envisible has a platform called Wholechain, a traceability platform. They provide over 10 species of frozen seafood to Topco Association of supermarkets in the US, where each of the items come equipped with a QR code. When Topco distributes the seafood to their member supermarkets they have the traceability of the seafood via the QR code. What Leandro likes about this solution is that each of the supermarkets do not need to adopt the blockchain technology they just need to adopt the Topco programme.

    Consumers in the supermarkets can scan the QR code and see where the seafood came from, how it came to its destination and is the sustainability of the supply chain.

    The solution is now in production.

    Monetisation

    Mastercard Provenance Solution uses a SaaS model for monetisation where payment is made upon usage of the solution. When you bundle this approach with a payment component, a transaction fee is charged that comes along with provenance and traceability.


    Ep. 169 – The future of governance and collaboration – insights from R3 Aug 29, 2021
    Show notes

    Alisa DiCaprio, is the Head of Trade and Supply Chain at R3 and also facilitates a lot of R3’s research. Whilst the concept of governance is familiar to many in the business community it has proven to be quite a challenge to blockchain business networks. In this podcast we discuss with Alisa, her latest research paper on the future of enterprise blockchain governance and collaboration. We cover some of the design and implementation of new business and technical models that will ensure that your blockchain journey is a success.

    What is blockchain?

    For Alisa, blockchain is just a database but what makes it different from other databases is that it’s decentralised that is global accessible. Like other digital technologies, blockchain requires the same adjustments to the global and commercial infrastructure.

    Discussing the future of governance and collaboration

    In July 2021, Alisa published a white paper entitled “The Future of Governance and Collaboration”. R3 began itself as a banking consortium and thus gained from the get go experience on how to build and manage consortiums. A lot of their consultations with companies building on Corda was about how do you manage a consortium?

    What they realised is that when projects go wrong it often is not because of the technology but because of the decision making process that doesn’t work or something with regards to governance. So, the white paper was an effort to set out the different examples of where governance has worked and all the different choices that need to be made. It sets out the policies that need to be thought of, it defines what is governance, and the questions that need be asked when building on blockchain technology.

    What is governance?

    Governance refers to the processes and the rules that determine how a system makes decisions as it evolves. It is something that needs to be thought of as early as possible as it establishes the core capability for a sustainable business network to last from its inception to the future.

    Are aspects of governance unique to blockchain?

    In legacy technologies there are well defined areas for adjudication when things go wrong. As blockchain is a new technology it doesn’t have those well defined adjudication history nor a long lasting legal infrastructure. A lot of today’s rules and regulations don’t apply to blockchain, so for this reason, governance becomes very critical. It contributes to its reputation as a technology that works.

    Why do blockchain projects fail due to governance?

    For Alisa, there are two types of characters that are early blockchain builders:

    • Entrepreneurs
    • Established businesses that may have an innovation fund or some money to play with

    Entrepreneurs who build on blockchain are usually new to the technology and are not necessarily thinking about establishing a governance structure. Established businesses which could be large companies or existing consortiums who are building on blockchain have an existing governance structure and they assume that it will work with blockchain and it doesn’t always.

    How do traditional business networks differ from blockchain business networks?

    Traditional business networks differ from blockchain business networks in three ways:

    1. Consortiums are considerably more common in the setup of blockchain business networks. The reason for that is because blockchain allows to innovate on a sector wide level rather than just a business level
    2. Blockchain business networks take a lot longer to implement than traditional business networks and also to change. Part of the reason is because it’s so new that it is unclear what the regulatory infrastructure is. You may need to establish a rulebook if the legislative component does not exist. And of course, there is a business culture change with suddenly the need to operate in a decentralised way.
    3. The role of the business network operator becomes a lot more important that it is in traditional networks

    Moving from a small centralised consortium to a larger decentralised one.

    In Alisa’s experience working with a small group of companies trying to affect governance isn’t necessarily easy. Each of those companies may be doing exactly the same process but they’re calling it different thing, they may not have a shared lexicon.

    Establishing this shared lexicon and a flow that works for those initial companies is important but equally important is to make it palatable for every new member of the consortium that joins. Thus, it becomes very important that the decisions structure that is developed has the ability to change as the number of new members grows the consortium.

    It is important not to lock in too many decisions early as the goal is to grow. You want other companies who join the consortium to see that the process that has been built is easier for them than the existing one and that they have a means to contribute to it.

    One of the pieces of work Alisa did was to build the standards body that was initially started with the Marco Polo banks which has since been handed over to the International Chamber of Commerce, now rebranded as the Digital Standards Initiative (DSI). During her time, she surveyed all members to answer 10 – 15 questions, which included questions like:

    • How many people should be on the board?
    • Should founding members have special rights once the consortium expands?
    • Should there be a membership fee?

    The output of that survey was used to help build the governance structure. What you don’t want to do is form a working group and ask these questions without having any idea what people incentives are. Because that means you’re working group meetings will take five hours and they’ll just be people yelling at each other.

    Having that document enabled Alisa to enter meetings knowing what each players want and have a point to discuss together to establish a common governance.

    Administrative governance

    The administrative governance structure is the longer term business and commercial activities that are associated within the business network.

    The body that administers these functions can be called the Business Network Governor (BNG). This is just a name, it can be a specific company, a group of companies, a board, or any structure. That entity is meant to facilitate the contractual relationship. It is generally responsible and accountable for establishing and maintaining governance policies, and accountable for their implementation and enforcement.

    Choosing a legal entity and where it is domiciled?

    Choosing a for profit or not for profit legal entity involves important choices such as how they generate revenue. For profits make their money by selling a product whilst a not for profit may generate its revenue from membership dues. Will membership dues be in a tiered way or just one price. Are they per individual members or via a corporate membership.

    Choosing what type of legal entity has implications on the jurisdiction that legal entity is in and will influence the structure of that entity.

    Policies

    Negotiating policies amongst members of a consortium forces the entities to talk about things like how to onboard and offboard an entity. This can be very important especially when thing go wrong. Alisa gave the example with B3 (Brazilian Stock Exchange) about what happens to a misbehaving node.

    B3 runs a blockchain network that essentially includes the entire sector. So, if a node is misbehaving, that raises the question, do you kick that node off the network? Because then if all the other companies in that whole entire sector are on the network, can you really exclude just one because then they don’t have access something that the rest of the industry does.

    Offboarding is often a lot more complicated and something that isn’t thought off until something goes wrong.

    Other policies to look at include: data privacy, data retention, prioritization of features, dispute management, inter-network policies, service level, legal contracting model, business model, data resiliency and system availability.

    Technical governance

    Technical governance includes the rules and processes that maintain the everyday functioning of the business network. Maintaining system integrity involves tactical decisions around shorter-term tasks like ensuring all of the nodes in the business network are upgrading at the same scheduled time. Technical governance is run by an entity called the business network which could be a number of different types of actors.

    Due to some of the difficult decisions that the business network has to take it’s important that this is a neutral entity. For example the off boarding policy is made by the administrative governor but its actual execution of the off boarding will be done by the network operator.

    _______________________________________________________________________________________________________

    This episode is brought to you by our friends and sponsors at R3. In this digital-first world, now more than ever, businesses need to modernize existing processes, systems and models – and enterprise blockchain provides the ideal solution for transacting directly and streamlining business operation.

    Developed by R3, Corda is light years ahead of other blockchain platforms in terms of privacy, security, scalability and interoperability. And–because Corda was built to meet the stringent requirements of highly-regulated industries, it can be used by firms of any type or size and in any industry.

    Blockchain applications built on Corda can reimagine and increase the potential of existing business networks, enabling direct and trusted transactions that eliminate friction and accelerate growth.

    Check out r3.com to find out more.


    1 2 3 19 Next

    Related Podcasts

    How I Built This with Guy Raz

    1

    How I Built This with Guy Raz Business
    Planet Money

    2

    Planet Money Business
    Inside Strategic Coach: Connecting Entrepreneurs With What Really Matters

    3

    Inside Strategic Coach: Connecting Entrepreneurs With What Really Matters Business
    BiggerPockets Real Estate Podcast

    4

    BiggerPockets Real Estate Podcast Business
    The Smart Passive Income Online Business and Blogging Podcast

    5

    The Smart Passive Income Online Business and Blogging Podcast Business
    A Thousand Natural Shocks With Gabe S. Dunn

    6

    A Thousand Natural Shocks With Gabe S. Dunn Business
    footer-logo

    Contact Us

    Toll Free: 844-670-7747

    Links

    • Home
    • Top Charts
    • Networks
    • Apps
    • Independents Podcasts
    • Podcast Advertising
    • Podcast News
    • Contact Us
    • About Us
    • Analytics & Insights

    Stay Connected

      Privacy, Terms of Use & Our Code of Ethics Protecting Content Creators Copyrights